Why Wall Street Got the Ultra Clean Sell-Off Backward
Ultra Clean fell 15% when Lam Research warned of supply bottlenecks, creating an inverted sell-off in the subsystem maker that builds the bottlenecked parts.
 Richard Tang · 3 min read
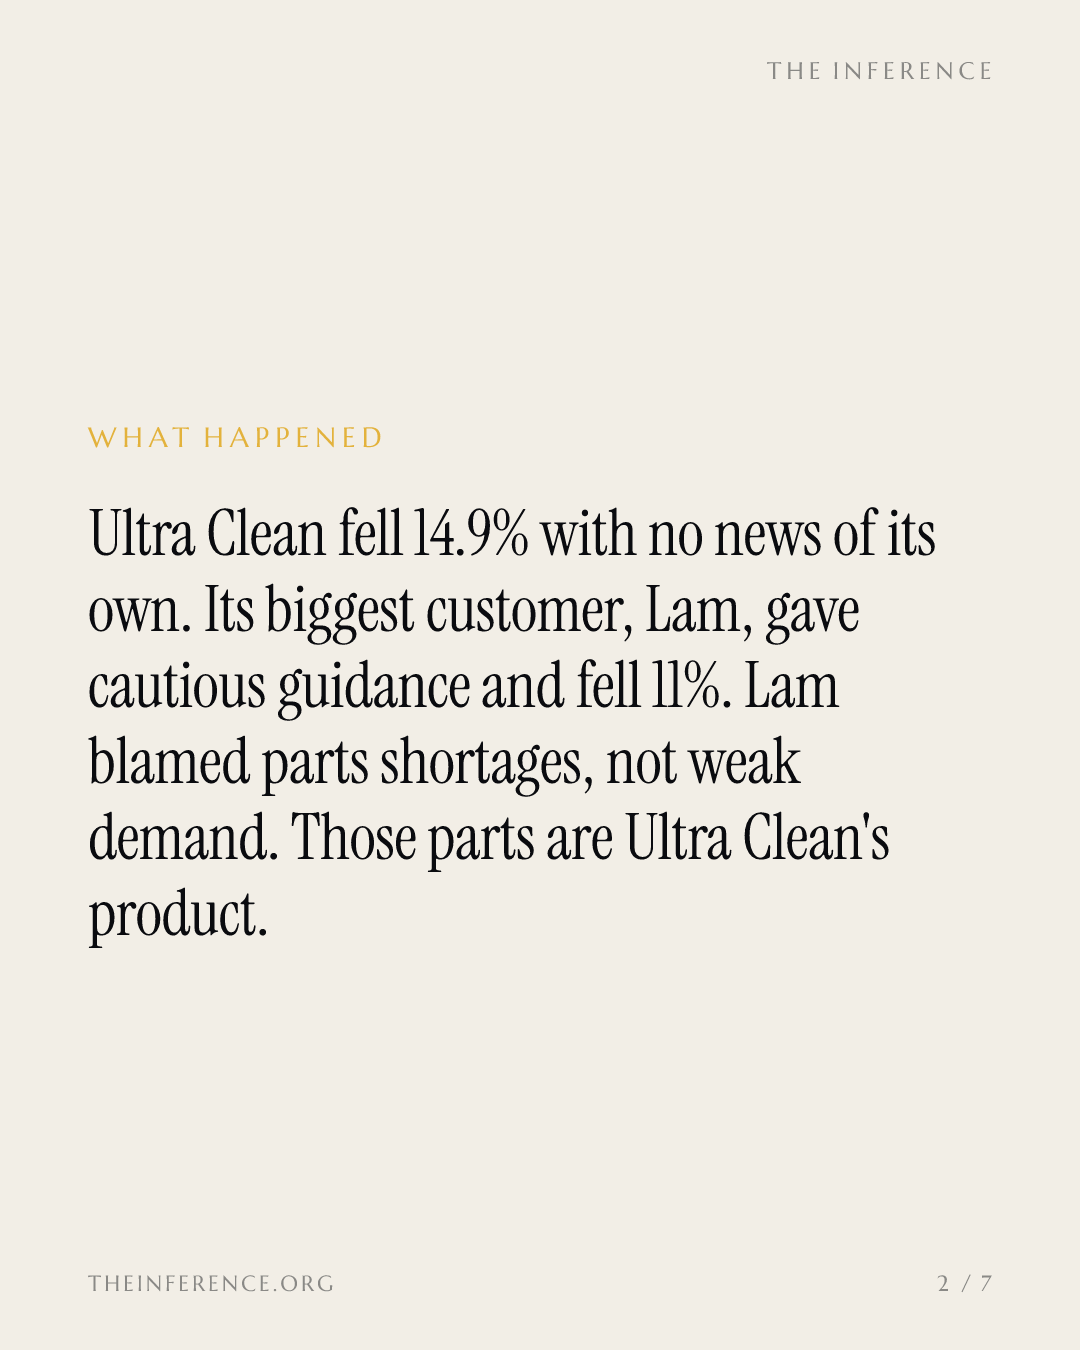
The stock market dumped semiconductor equipment supplier Ultra Clean Holdings+2.32% — Ultra Clean Holdings, up 2.32 percent today by 14.9% on October 22, 2026, without a single press release from the company 12. That same morning, its biggest customer, Lam Research+0.22% — Lam Research, up 0.22 percent today, guided its December-quarter revenue to $8.60 billion—above the $8.53 billion consensus—yet fell 11% 3. The sell-off was indiscriminate: investors panicked over toolmaker guidance while ignoring that the toolmakers are choked for parts 34.
The supplier got sold because the customer cannot ship fast enough
The drop in Ultra Clean (ticker UCTT) exposes an analytical failure in the semiconductor supply chain 12. Lam Research constitutes roughly 40% of Ultra Clean's total revenue, with Applied Materials+1.09% — Applied Materials, up 1.09 percent today bringing the top two buyers to about 62% of sales 6. When Lam fell, algorithmic and retail selling dragged Ultra Clean down with it 135.
Two customers are about 62% of Ultra Clean's revenue
- Lam Research4040%
- Applied Materials2222%
- Other customers3838%
Data
| Slice | Value | Share |
|---|---|---|
| Lam Research | 40 | 40% |
| Applied Materials | 22 | 22% |
| Other customers | 38 | 38% |
A customer's bottleneck is a supplier's backlog
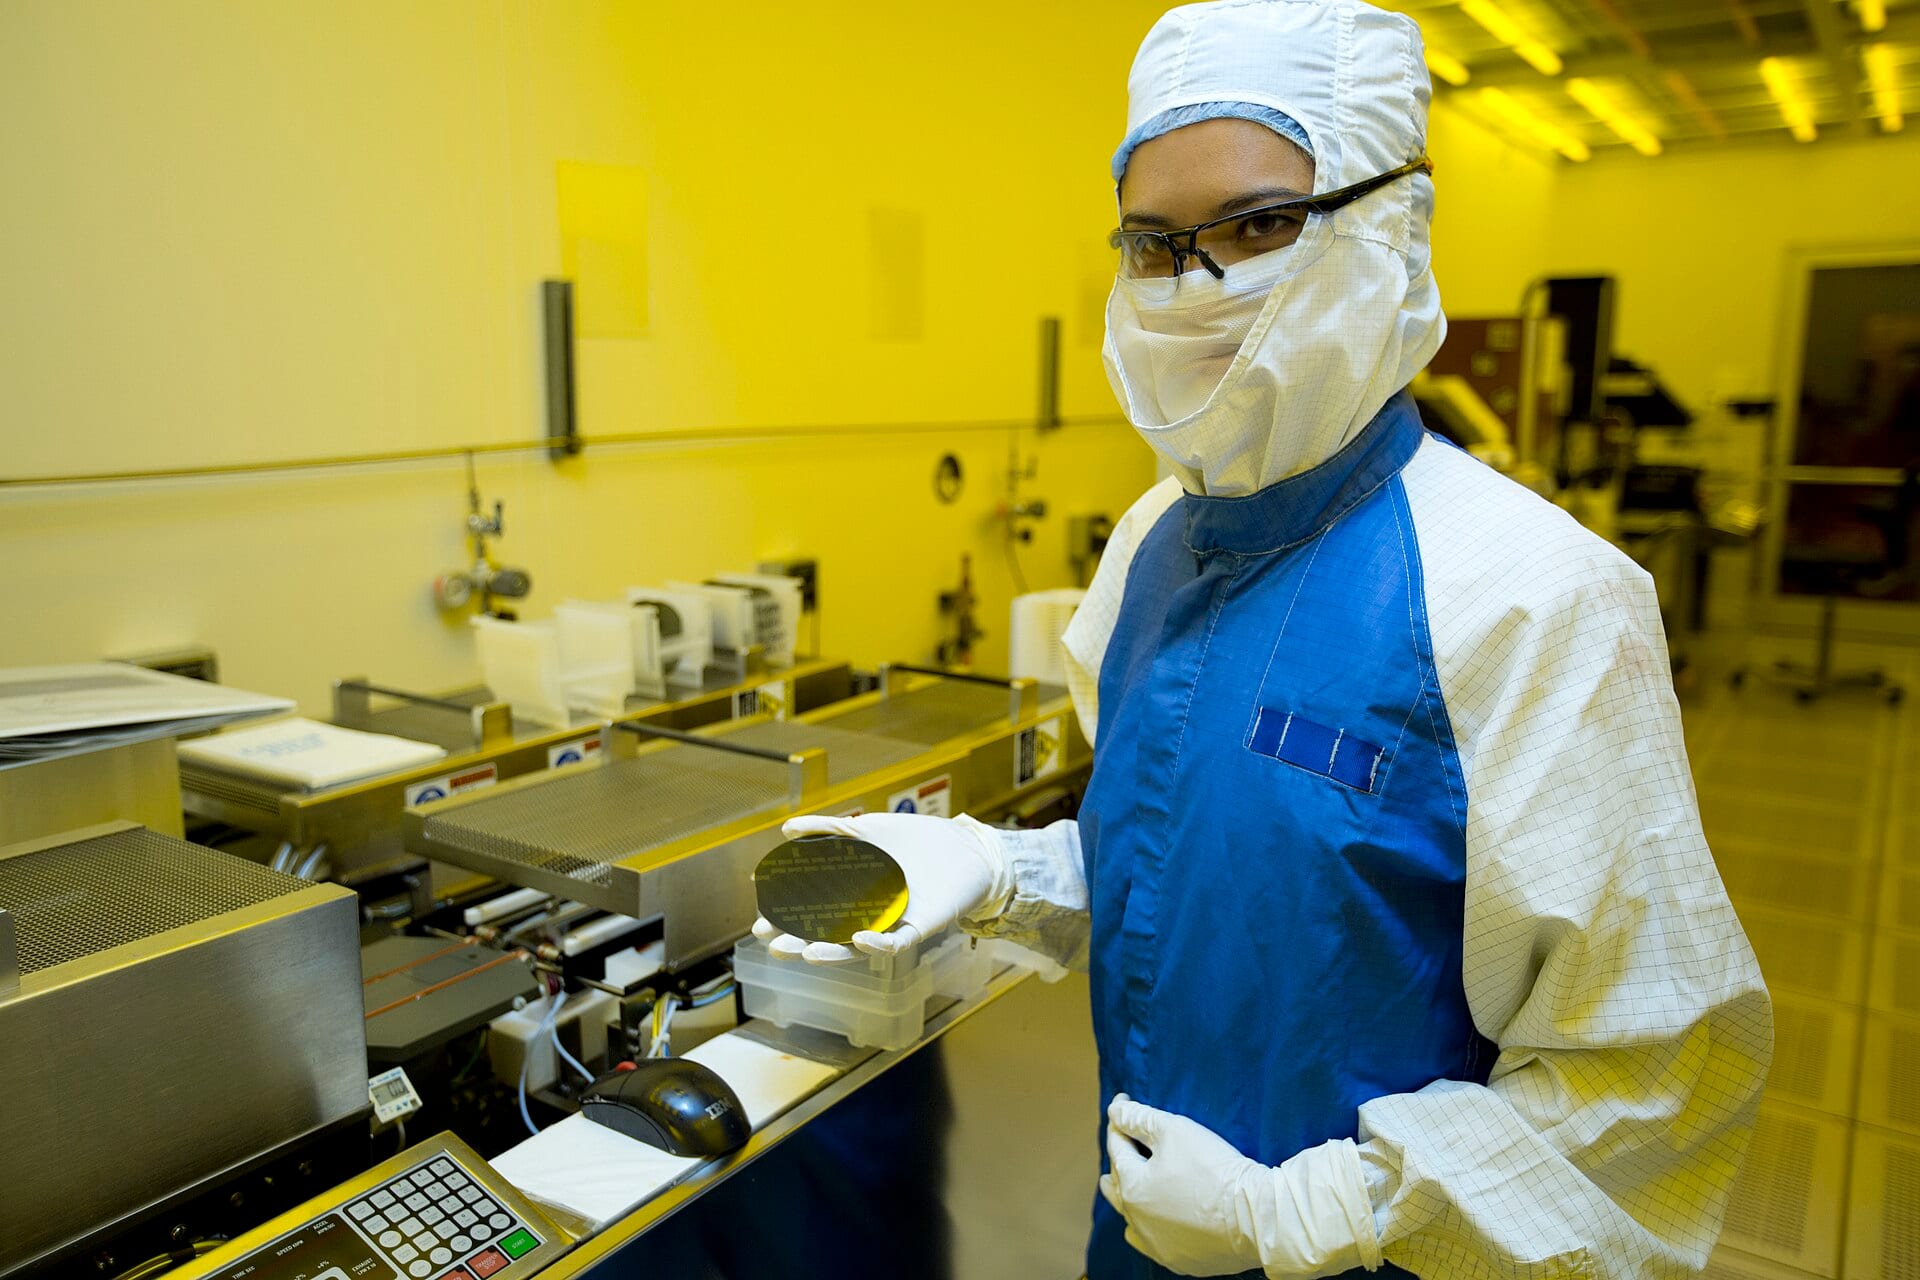
Yet on its earnings call, Lam pointed to supply bottlenecks where component demand is outstripping toolmakers' build capacity 45. Ultra Clean manufactures the critical gas delivery systems, liquid chemical delivery modules, and wafer-cleaning subsystems that sit inside Lam's etch machines and Applied's deposition systems 67. The buyer did not issue a weak outlook because chipmakers stopped ordering tools; it guided conservatively because component suppliers cannot assemble subsystems fast enough 45. Selling the subsystem builder because the equipment assembler is backlogged gets the bottleneck entirely backward 45.
Working capital explains the margin squeeze, not falling demand
Ultra Clean's upcoming third-quarter report on October 27, 2026, will test whether this valuation disconnect holds 28. In the second quarter of 2026, Ultra Clean reported revenue of $644.9 million, expanding 24.3% year-over-year, alongside non-GAAP earnings of $0.70 per share 26. Management guided third-quarter revenue to a range of $700 million to $750 million, with adjusted earnings of $0.83 to $1.03 per share 26.
Revenue re-accelerated in 2026 and guidance implies another step up
- Revenue
- Estimate
Data
| Revenue | |
|---|---|
| Q2 '24 | $516.1M |
| Q3 '24 | $540.4M |
| Q4 '24 | $563.3M |
| Q1 '25 | $518.6M |
| Q2 '25 | $518.8M |
| Q3 '25 | $510M |
| Q4 '25 | $506.7M |
| Q1 '26 | $533.7M |
| Q2 '26 | $644.9M |
| Q3 '26 (estimate) | $725M ($700–750M) |
The cash drain is inventory and clean rooms, not unsold goods
The single genuine operational vulnerability sitting on Ultra Clean's ledger is cash conversion 6. In the second quarter, operating cash flow ran at negative $41.1 million as cash balances slipped to $255.9 million 6. That cash drain was not caused by unsold finished goods sitting idle, but by aggressive inventory accumulation and clean-room buildouts in Malaysia and Singapore designed to support higher customer run rates 6. Ultra Clean must tie up significant working capital in titanium, specialized valves, and high-purity piping before it can bill Lam or Applied Materials 67.
Dislocation creates a clear catalyst into the October 27 print
At a market capitalization of $2.4 billion, Ultra Clean now trades around 69% below its 52-week peak of $144.22 2. On October 19, 2026, Oppenheimer reaffirmed an Outperform rating with a $150 price target, highlighting capacity additions and original equipment manufacturer integration 2. Freedom Broker also initiated coverage with a Buy rating and a $127 target earlier in the month 2.
Analyst targets of $127 to $150 versus a stock implied near $45
Data
| Value | |
|---|---|
| Oppenheimer target | $150 |
| 52-week peak | $144.22 |
| Freedom Broker target | $127 |
| Implied price now | $44.7 |
Wall Street consensus targets $727.55 million in revenue and $0.938 in adjusted per-share profit for the print 2. If Ultra Clean confirms that subsystem deliveries remain on schedule, the disconnect between Lam's backlog and Ultra Clean's valuation should narrow quickly 24. For technology investors, the company represents a classic supplier squeeze: the market dumped the bottleneck instead of paying for it 45.
What happens next
LRCXDo subsystem deliveries stay on schedule, and does cash conversion improve?
The case for
Lam Research, about 40% of Ultra Clean's revenue, blames component shortages rather than demand for its cautious December-quarter view, which points to delayed shipments instead of lost orders
The case against
Operating cash flow ran at negative $41.1 million in Q2 and cash slipped to $255.9 million, so the growth is being financed by working capital
- Tuesday Oct 27, 2026Ultra Clean third-quarter results.
Get our follow-up when these land
Free. We'll email you when we publish on Lam Research, and send our free weekday newsletter. Unfollow in one click.