Besi booked record €342.6 million orders and 324% profit growth; the stock is down more than 50%
Record orders of €342.6 million and a 323.7% jump in net income bought Besi's shares no relief on results day. Investors are pricing deliveries pushed into 2027 and ASML's 27 patent filings, not this quarter's numbers.
 Vincent Jiang · 3 min read
Besi+4.40% — Besi, up 4.40 percent today, the Dutch maker of the machines that weld stacked chips together, posted the strongest order quarter in its history on October 22, and the shares slipped 2.55% to €158.30, leaving the stock more than 50% below its 52-week high of €328.40 125. Order intake hit a record €342.6 million, up 96% year on year and 17% on the quarter, against the €298 million analysts polled by Visible Alpha expected 3.
The profit line kept pace. Revenue rose 113.6% to €283.4 million, net income jumped 323.7% to €107.2 million, and gross margin reached 65.2%, three points above a year earlier 4.
The order book keeps outrunning the shipments
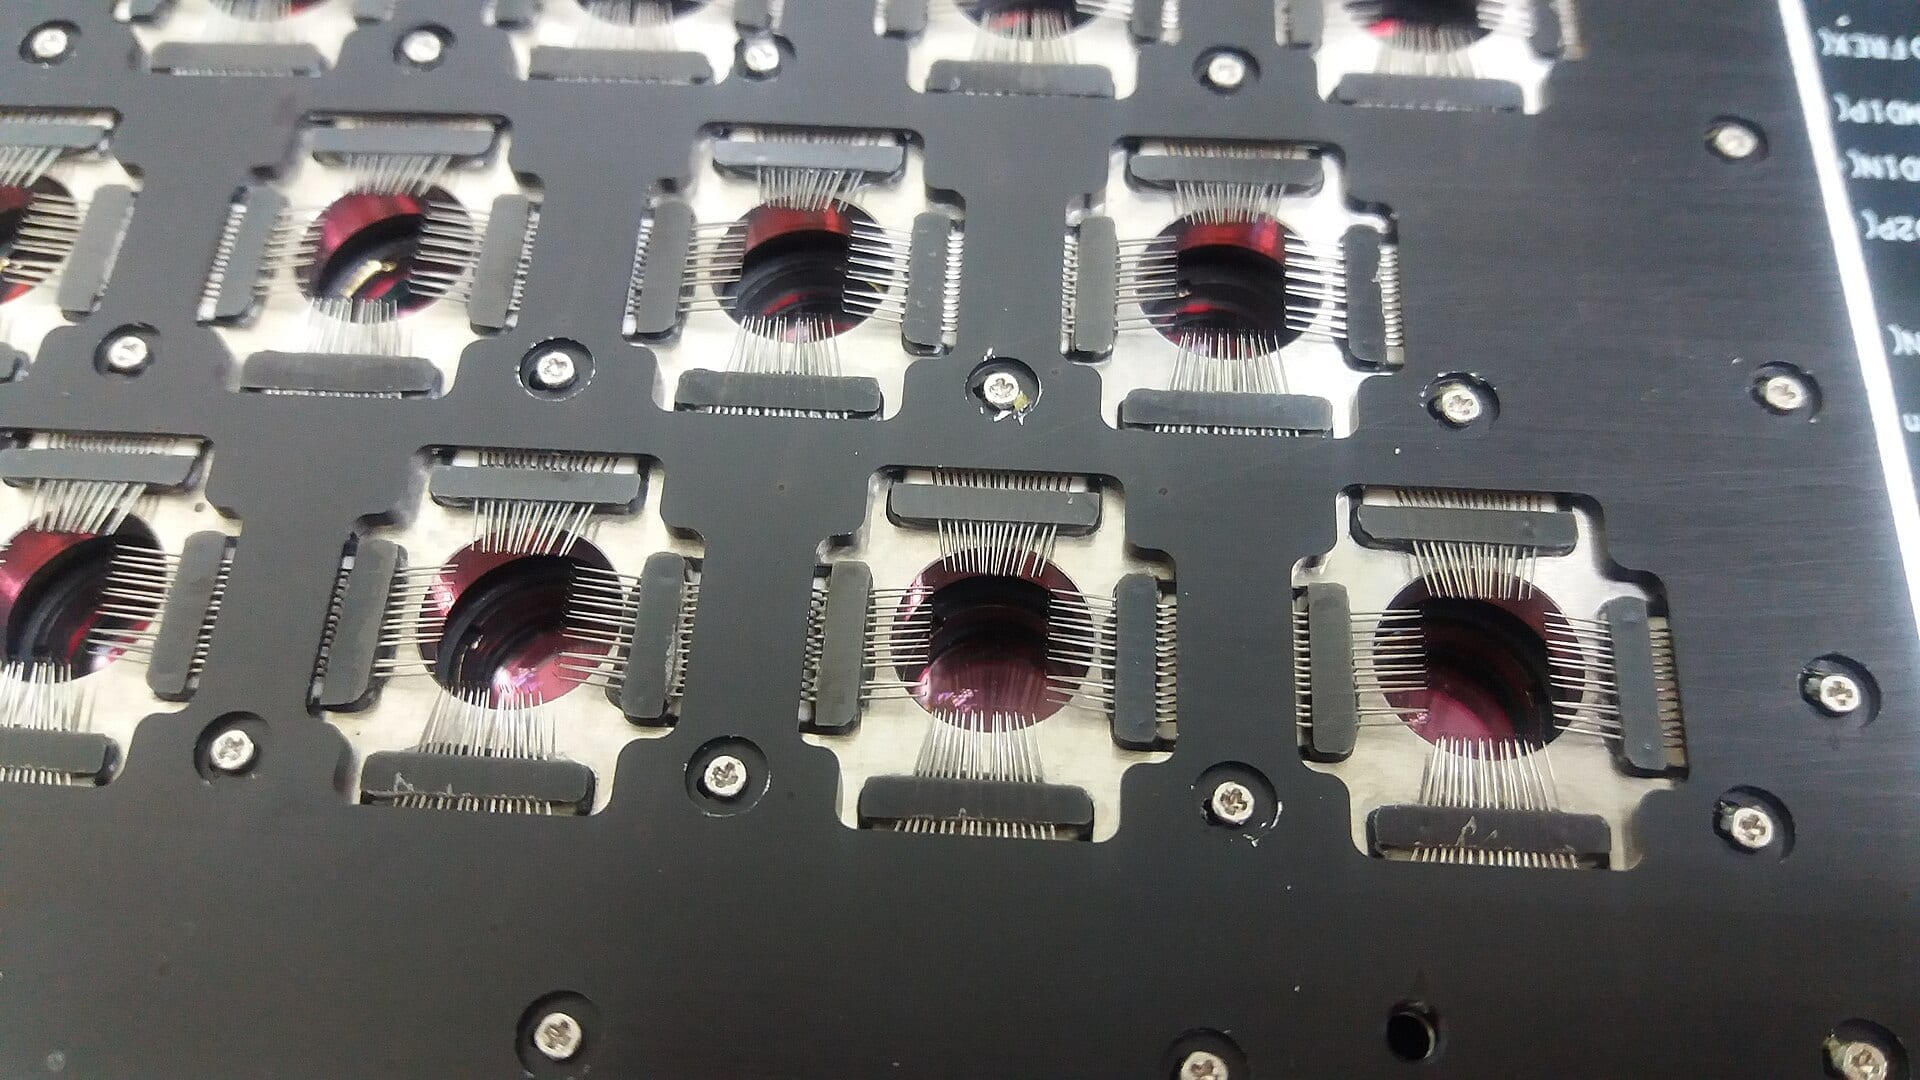
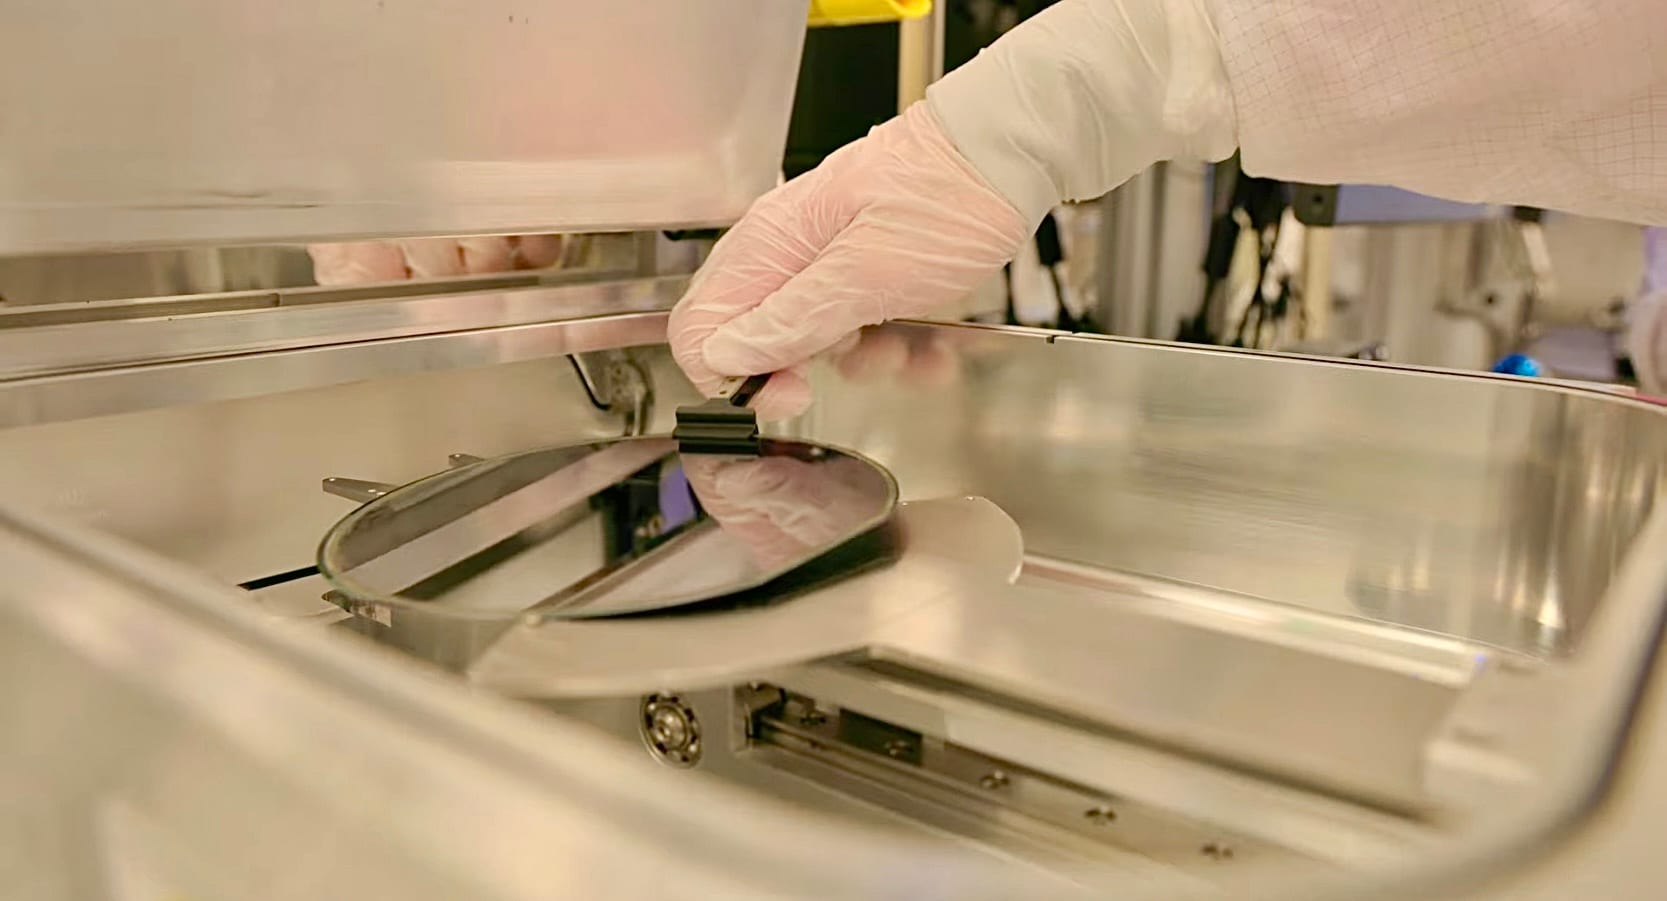
Hybrid bonding, which welds the silicon faces of stacked chips together instead of joining them with solder bumps, carried the quarter. Orders for those systems more than doubled in the first nine months of 2026 against all of 2025, and the customer list has grown to 23, with cumulative demand above 215 systems 13. Orders ran ahead of shipments, a book-to-bill of about 1.2, roughly €1.20 of new orders for every euro delivered 5, after first-half bookings of €562.6 million against first-half revenue of €434.7 million 6.
Order intake ran ahead of revenue again in Q3, and Q4 is guided flat
- Order intake
- Revenue
- Estimate
Data
| Order intake | Revenue | |
|---|---|---|
| Q2 2026 | €292.9M | €249.9M |
| Q3 2026 | €342.6M | €283.4M |
| Q4 2026 guide (estimate) | — | €283.4M |
Two questions the quarter cannot answer
The flat guide is the trigger. Fourth-quarter revenue is guided broadly unchanged from the third quarter's €283.4 million, give or take 5%, below the €291.5 million analysts polled by LSEG expected, and some customers asked for third-quarter deliveries to land in the first half of 2027 3. The orders stay on the books; Besi calls the shift timing, and ING analyst Marc Hesselink called the shortfall timing-related 35.
The memory market may not convert until 2029
The first open question is memory. Investors fear Micron−4.81% — Micron, down 4.81 percent today and SK Hynix−5.86% — SK Hynix, down 5.86 percent today will be slow to adopt hybrid bonding for high-bandwidth memory, the DRAM stack beside every AI chip, and SemiAnalysis, the research firm behind the patent analysis, expects adoption to slip to 2029 or later 35. JPMorgan cut its target from €342 to €275 on October 19 on a likely adoption delay, the 23-analyst consensus fell to €268 from €290, and UBS at €159 sat below the €162.15 price of October 21 26.
UBS now values Besi below the market, and the consensus target fell €22 in days
Data
| Value | |
|---|---|
| UBS target | €159 |
| Share price, Oct 21 | €162.15 |
| Consensus target | €268 |
| JPMorgan target | €275 |
ASML has patents, not yet a product
The second is ASML−4.99% — ASML, down 4.99 percent today, the world's biggest chip-equipment maker. SemiAnalysis read 27 of its patent filings on October 16 as a rival bonding tool in development; Besi fell 3% that day, and ASML has confirmed nothing 7. Bank of America+0.66% — Bank of America, up 0.66 percent today cut the stock to neutral on October 6, saying the threat was not reflected in the price 8. Chief executive Richard Blickman: "We do not view ASML as a hybrid bonding competitor," citing joint work on chip-placement precision 3.
Cash buys the argument time
The balance sheet funds the wait. Net cash reached €246.6 million at the end of September, up from a negative €7.8 million a year earlier, and a €100 million buyback starts on October 27 14. Besi paid an average €210.67 a share for its own stock last quarter, about a third more than the current price 4.
Who gets paid, and when
The record orders settle that demand for advanced packaging is real and under contract. The delivery calendar stays open, and that is the risk a halved price is charging for. Holders have already paid for the delay; a buyer at €158 gets paid only if the 2027 deliveries ship. Watch whether fourth-quarter orders again outrun revenue, and whether the memory makers commit.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.