Camtek booked $800 million of orders, the stock fell 8% intraday, and gross margin stalled at 51.1%
Twelve analysts still average a $170.20 target on Camtek, 68% above the close, while the COO hedged his own recovery timeline on the earnings call: "We're not sure about it." The record quarter is booked; the argument is whether it converts at improving margins.
 Vincent Jiang · 2 min read
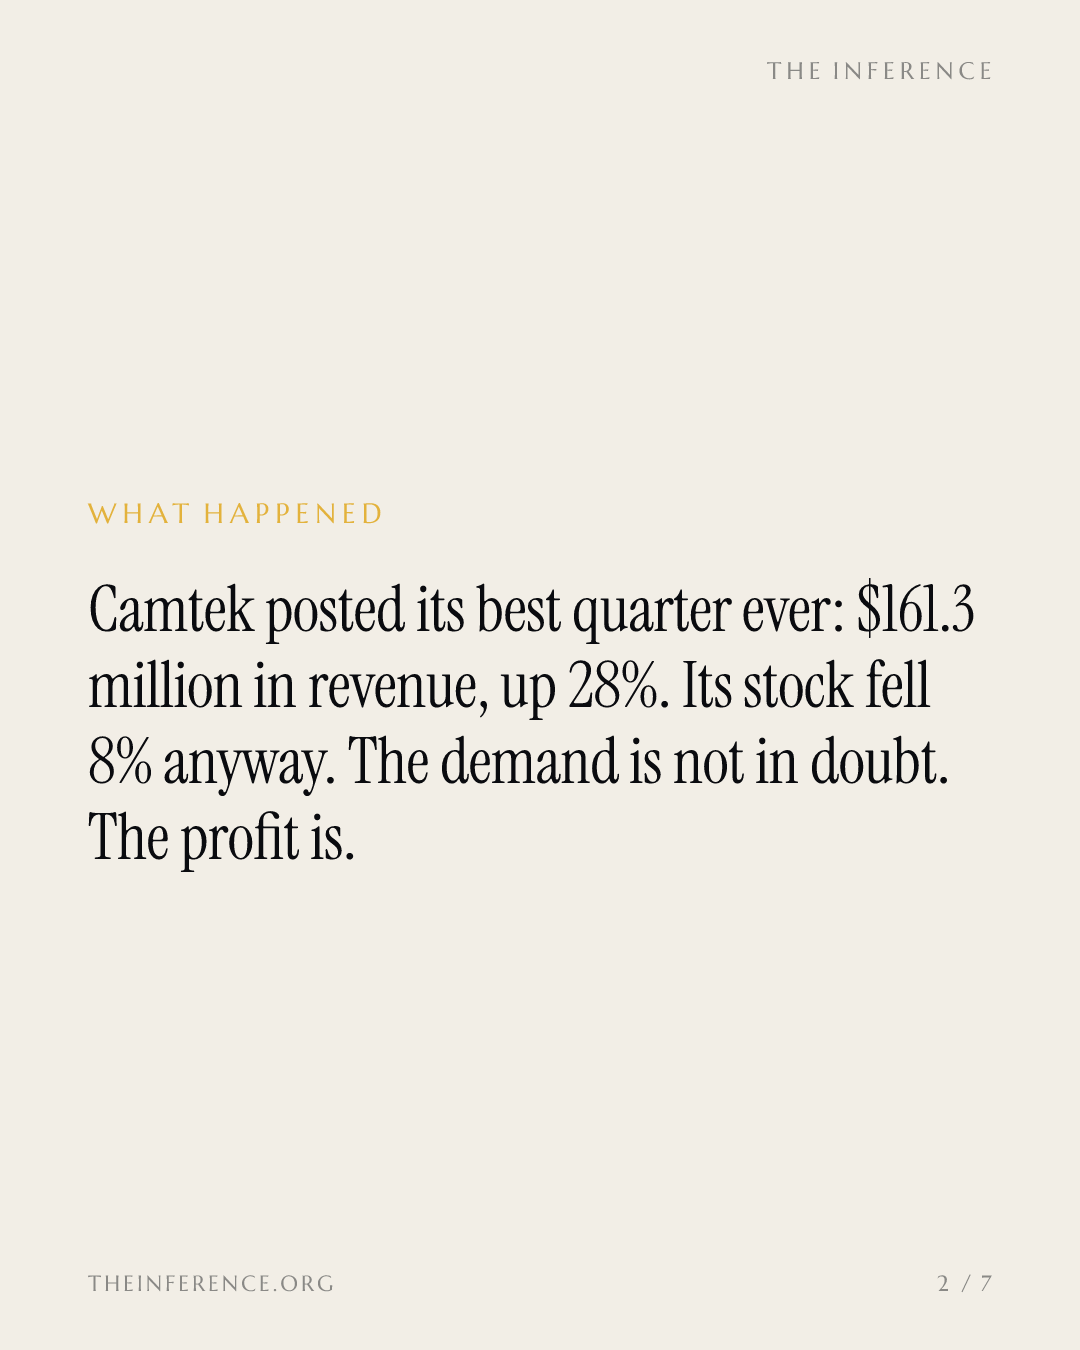
Camtek+2.11% — Camtek, up 2.11 percent today, the Migdal HaEmek company whose Hawk and Eagle G5 machines inspect and measure AI chips and HBM memory stacks before they ship, posted the best quarter in its history on November 4 and its shares fell anyway, down about 8% intraday at $103.73 1 and closing near $101.46 3.
Record revenue of $161.3 million, up 28% from a year earlier and about 80% from advanced packaging tied mostly to AI demand, was already public: the company pre-announced $160 to $161 million in mid-October, and the November 4 filing is the first full report confirming it, alongside details the market did not like 12.
The prize is real. Camtek has taken in more than $800 million of orders since January, and CEO Rafi Amit says customers, including Chinese ones, have reserved delivery slots through 2027, giving the company about a year of visibility for the first time in its history 12. The 2027 guide above $800 million sits well past FactSet's−4.00% — FactSet, down 4.00 percent today $756.2 million estimate 34.
The fight is margin, not demand
Gross margin sat at 51.1%, essentially flat against 51.4% in the second quarter, and CFO Moshe Eisenberg called it "a bit disappointed," blaming costlier parts and materials plus a stronger shekel 1. Adjusted earnings of $0.99 a share landed a cent under the FactSet estimate 4.
The same call produced the sentence the bears will keep: pressed on when memory and CPU shortages ease, COO Ramy Langer said three to six months, then added, "We're not sure about it" 1. The shortage is industry-wide: Q3 DRAM revenue approached $200 billion, up 369% year over year 8.
Margins have plateaued near 51% while the AI order book booms
Gross margin has been stuck near 51% even as the AI order book booms
Data
| Gross margin (%) | |
|---|---|
| Q1 '24 | 46.1 |
| Q2 '24 | 49.9 |
| Q3 '24 | 49.7 |
| Q4 '24 | 49.6 |
| Q1 '25 | 51 |
| Q2 '25 | 50.8 |
| Q3 '25 | 50 |
| Q4 '25 | 50 |
| Q1 '26 | 50.1 |
| Q2 '26 | 50.1 |
| Q3 '26 | 51.1 |
The counterpoint: is 2D inspection a price war?
Morgan Stanley+0.78% — Morgan Stanley, up 0.78 percent today downgraded the stock to Underweight on November 2, arguing 3D metrology is defensible but 2D inspection risks becoming a pricing fight 3. Needham and Evercore−0.16% — Evercore, down 0.16 percent today kept Buy and Outperform but cut targets to $130 from $170 and $115 from $155 67. The mean target of 12 analysts, $170.20, sits 68% above the close 3.
Even after the cuts, the analyst mean sits 68% above the close
Data
| Price target | |
|---|---|
| Close, Nov 5 | $101.46 |
| Evercore target | $115 |
| Needham target | $130 |
| Analyst mean | $170.2 |
What decides it
The guide is a backlog statement until margins prove otherwise. Watch the first-quarter 2027 gross margin 1: if Eisenberg's gradual improvement shows up on schedule, the doubters are wrong; if parts costs and the shekel hold, the $1.2 billion target comes with thinner economics than advertised.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.