Micron's Chinese rival CXMT held 9% of world DRAM revenue in Q3, down from 10%, and does not yet sell HBM4
Counterpoint's quarterly tracker, out on November 5, counts ChangXin Memory at 9% of world DRAM revenue, down from 10%, in a record quarter driven by price. The chip billed as China's answer to Micron is earning the cycle's margin while missing the product, HBM4, where the next share is decided.
 Richard Tang · 3 min read
The number investors quote for China's memory champion comes from Dan Niles, the fund manager who warned this week that Micron's real risk is CXMT−3.54% — CXMT, down 3.54 percent today: about 8% of the DRAM market today, with an aim of 20% by 2028 2. Counterpoint Research's quarterly table, published on November 5, counts differently. 2
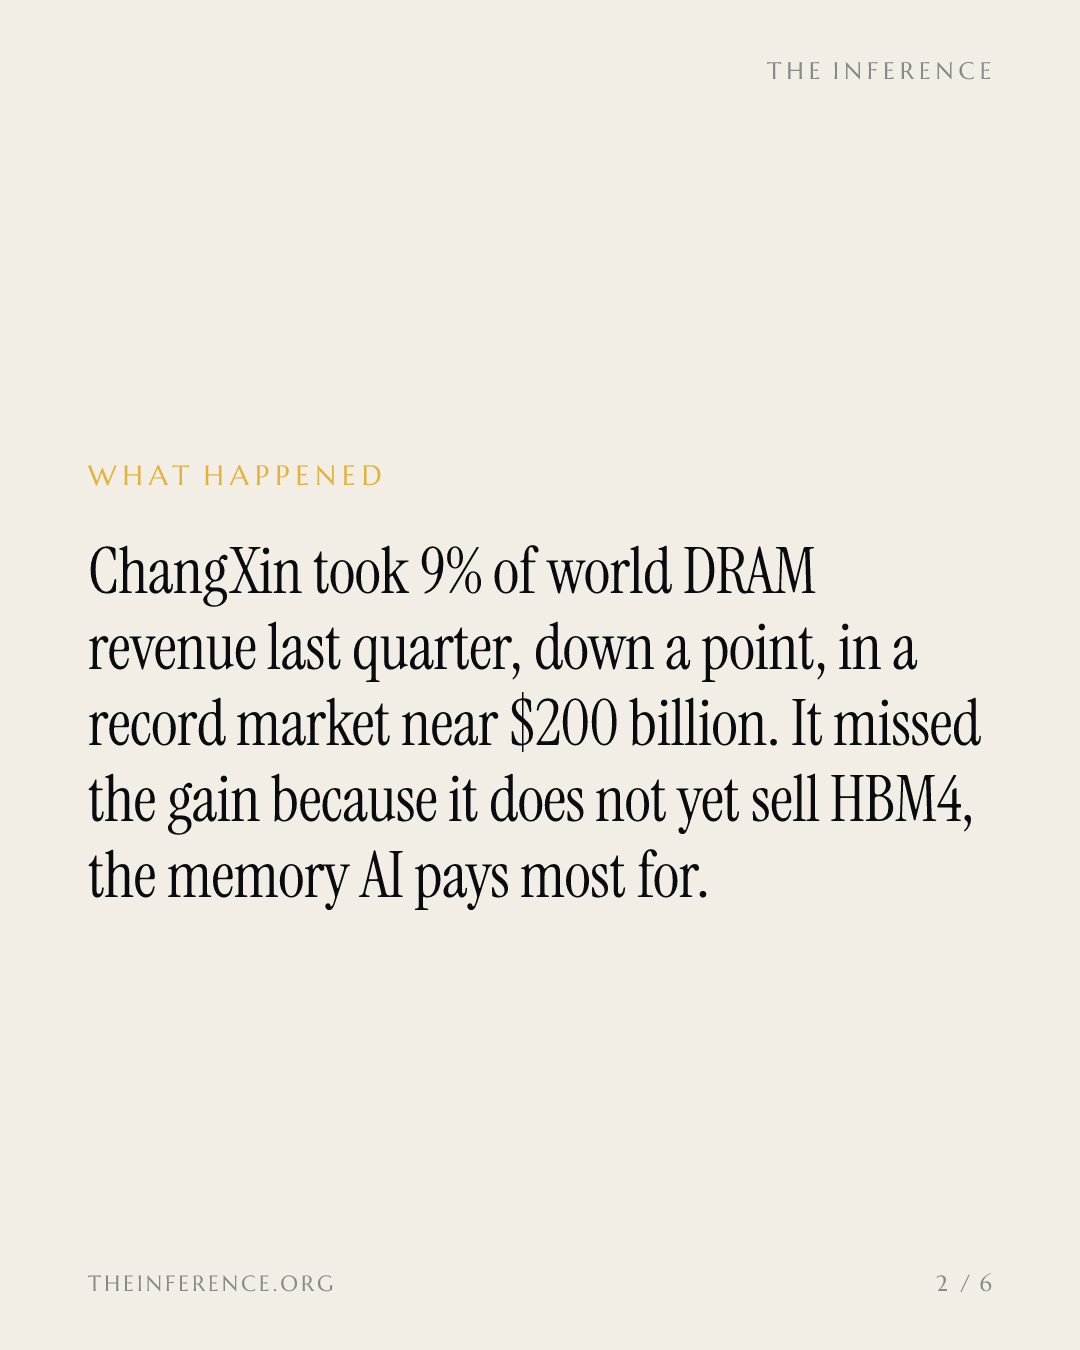
ChangXin Memory Technologies took 9% of world DRAM revenue in the third quarter, a point lower than in the second, in a global market that hit a record near $200 billion 1. The climb case rests on the margin. The share table is the counter-evidence. 1
A price-led boom pays the seller with the higher-value chip
Counterpoint's tracker explains why both things are true at once. Third-quarter DRAM revenue was a price story, not a volume story: bit shipments grew about 4% while selling prices set records, and commodity DDR and LPDDR actually outgrew HBM. 3
CXMT sells commodity DRAM and says its products are priced on par with overseas rivals, so it collects the same price rise everyone else collects and cannot outgrow the market. Samsung and SK hynix−11.68% — SK hynix, down 11.68 percent today expanded supply of higher-value products instead, and SK hynix's revenue rose more than 40% from the second quarter, lifting its share three points 4 1. CXMT's revenue rose with the market because its prices match rivals; its share fell because its products do not. 4 1
ChangXin holds 9% of DRAM revenue, down a point, against a 20% by 2028 target
The bear case prices 20% by 2028; the Q3 table shows 9% and Counterpoint sees it lower
Data
| Value | |
|---|---|
| Samsung | 38% |
| SK hynix | 29% |
| Micron | 21% |
| CXMT | 9% |
The next point of share gets decided where CXMT does not yet sell
Counterpoint expects ChangXin's share to decline further in the fourth quarter, as the Korean makers begin shipping HBM4, the memory class AI data centers pay the most for 1 5 4. SK hynix brought HBM4 into mass production this quarter and says its memory is sold out through 2029; CXMT's furthest product on that front is a first batch of HBM3E samples. 1 5 4
The climb case is real, and it is dated. CXMT's sixth-generation 4F² platform, the density design Micron−13.77% — Micron, down 13.77 percent today has ruled out, completed engineering-sample validation, and its third-quarter gross margin of 89.53% was higher than Micron's 6 4. But the first server-grade samples are due only by December 31, and the company has disclosed no mass-production timeline. 6 4
Micron's answer comes on December 16, and its own supply just wobbled: it suspended work on its $4.5 billion Taiwan fab over a pay dispute, in a country that makes about 60% of its DRAM output. 7
What the table says about the risk
Read this week as a dispute over the climb, not a dispute over demand. The AI buildout is real and CXMT is a genuine long-term competitor; the buildout also has a funding question, and Beijing is currently defending the market CXMT trades in. State-backed funds put 76.7 billion yuan into nine favored exchange-traded funds on November 3. 8 6
CXMT's chairman proposed enlarging the company's buyback the next day. That support holds the price while the fundamentals wait on the two December dates. What the table supports is the companies shipping HBM4 8 6. What it does not support, yet, is paying for a 20% share that appears nowhere in the revenue count. 8 6
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.