Vistra's $1 Billion AI Bet Changes Who Carries the Risk
Vistra can sell power to the AI buildout and help finance it. Owning connected plants is a real advantage; committing shareholder cash to the projects that buy from them is a different bet.
 Vincent Jiang · 6 min read
Jim Burke bought more Vistra−15.07% — Vistra, down 15.07 percent today shares through his family partnership on August 31 and September 1.1
The preferred-supplier bet
His company is making a larger commitment: up to $1 billion to Helix Digital Infrastructure, the venture launched with KKR, Kuwait Investment Authority and Nvidia−2.14% — Nvidia, down 2.14 percent today. Vistra becomes both an investor in AI infrastructure and its preferred power provider. That changes the investment case. Selling electricity to an expanding industry and helping finance its expansion expose shareholders to different risks.2,3
The attraction is clear. A company that already owns operating power plants can negotiate with customers whose computing ambitions depend on electricity arriving on schedule. The complication is what management does with that advantage. Shareholders can receive cash from scarce assets, or see that cash committed to projects whose returns depend on construction, financing and customer adoption. Vistra increasingly offers both.
Time is the moat
Its strongest advantage is time. Berkeley Lab's May 2026 interconnection study found that projects completed in 2025 took a median of more than five years from requesting a grid connection to commercial operation. An existing connected plant has already cleared a process that a proposed competitor still faces. For a customer trying to open a data center, reliable delivery on time can matter more than a cheaper promise years away.4
What Meta's contracts actually monetize
Meta's+1.34% — Meta, up 1.34 percent today nuclear contracts show how that advantage becomes commercial. The January agreements cover 2,609 megawatts, including 2,176 from operating plants and 433 from planned capacity increases. Only about 17% represents additional generating capacity, calculated from the disclosed amounts. Most of the transaction monetizes an existing fleet through long contracts. Meta confirms that the plants continue supplying the regional grid.5,6
That distinction matters. Long contracts can reduce exposure to merchant electricity prices while improving the economics of existing production. They also create a schedule: Vistra expects full delivery from the operating capacity by the end of 2027, while the additional capacity ramps through 2034. Investors should value those cash flows on different timelines. They should also resist assigning a precise contract valuation when prices and detailed termination economics remain undisclosed.5
Comanche Peak illustrates the same timing issue. Its twenty-year AWS agreement covers 1,200 megawatts, with delivery expected to begin in late 2027 and reach the full amount by 2032. The plant exists today; the entire contract contribution does not.3
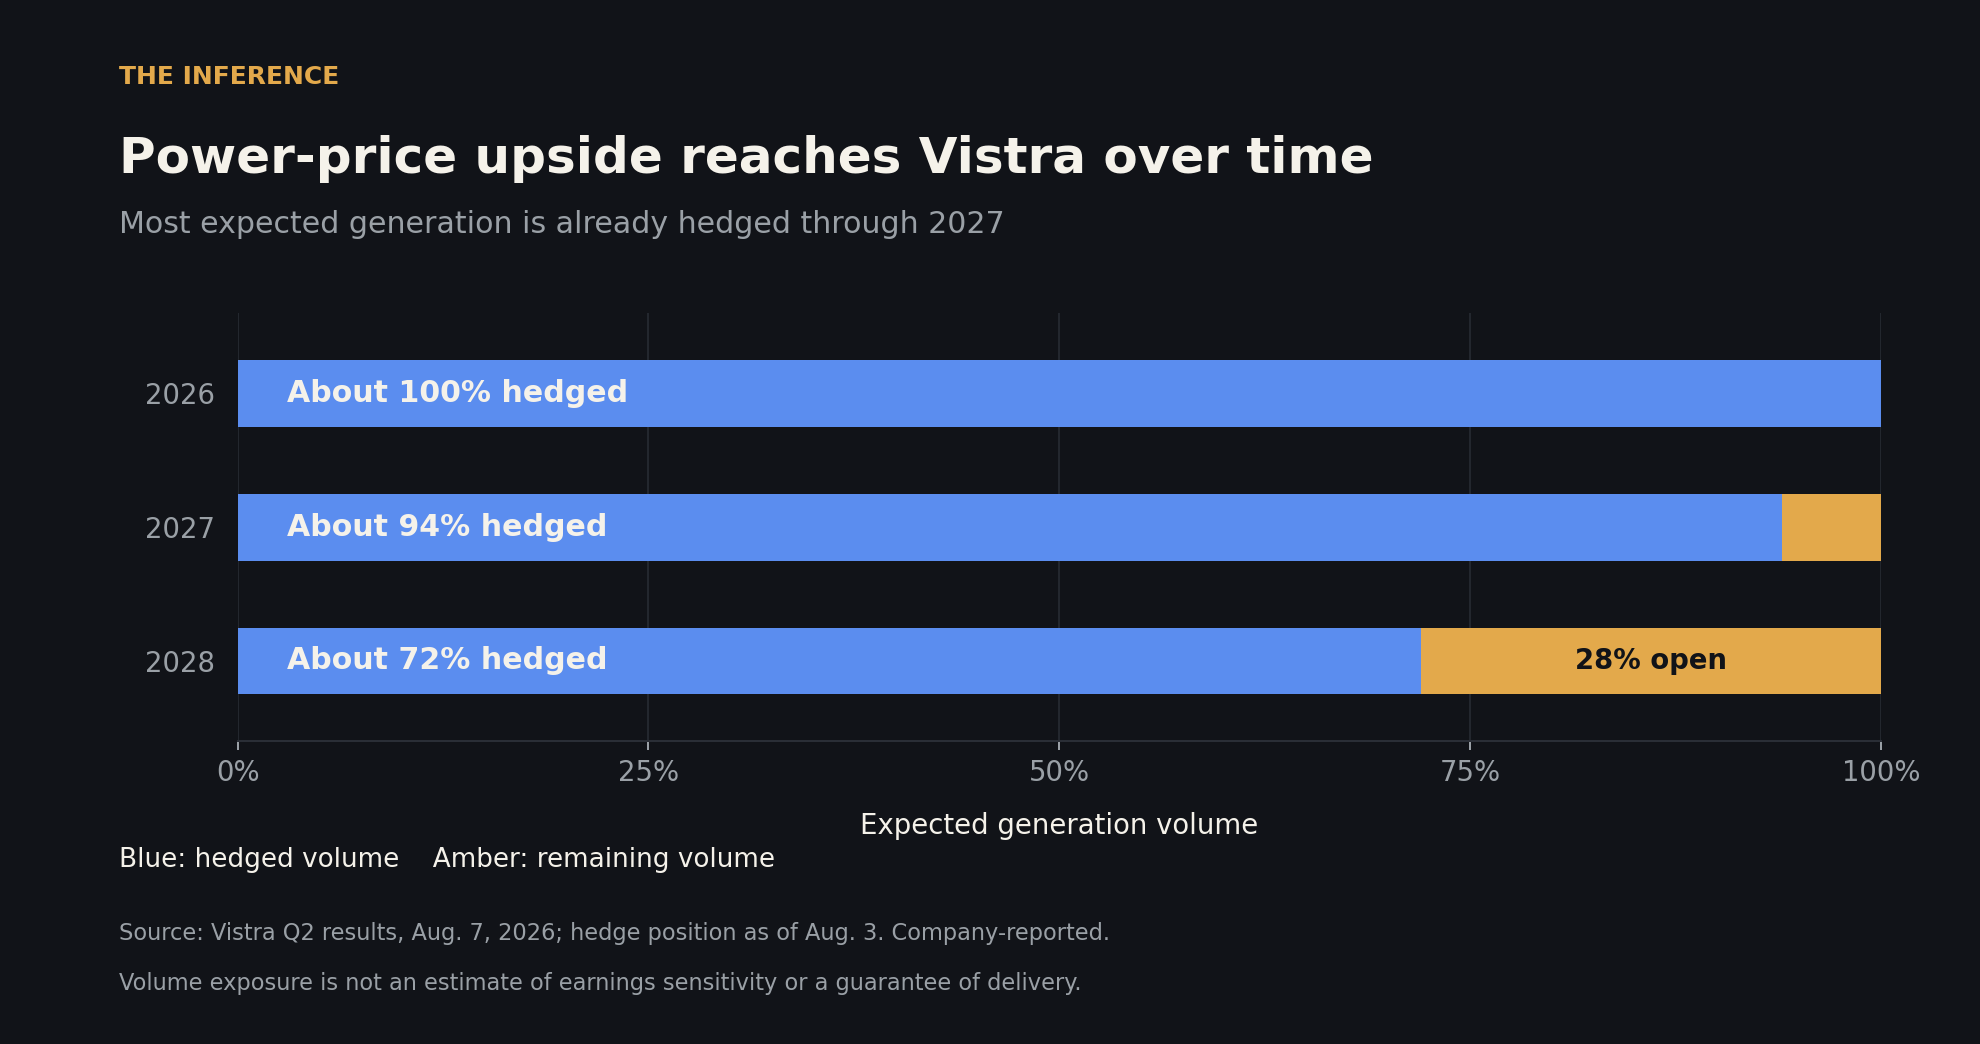
Near-term repricing is limited. As of August 3, Vistra had hedged approximately 100% of expected 2026 generation, 94% for 2027 and 72% for 2028. Investors need to examine contract resets and delivery reliability. Gas plants must also cover fuel costs; electricity prices alone cannot establish their profitability.8,3
The cash-flow math gets demanding
The valuation becomes more demanding when we follow the cash. Vistra's reaffirmed 2026 forecast is $3.925 billion to $4.725 billion of adjusted free cash flow before growth. That is a company-defined, non-GAAP measure. It excludes growth investment and adjusts for working capital and margin deposits, among other items. It is useful for assessing the operating business, but it is not the cash automatically available to common shareholders.7
At September 14's closing price of $140.73, using the approximately 336 million shares reported on August 3 gives an estimated equity value of $47.3 billion. The forecast midpoint of $4.325 billion is about 9.1% of that value. That looks attractive until the words "before growth" receive the same attention as the percentage. The share count is dated, so this is an approximate valuation snapshot.7,9,10
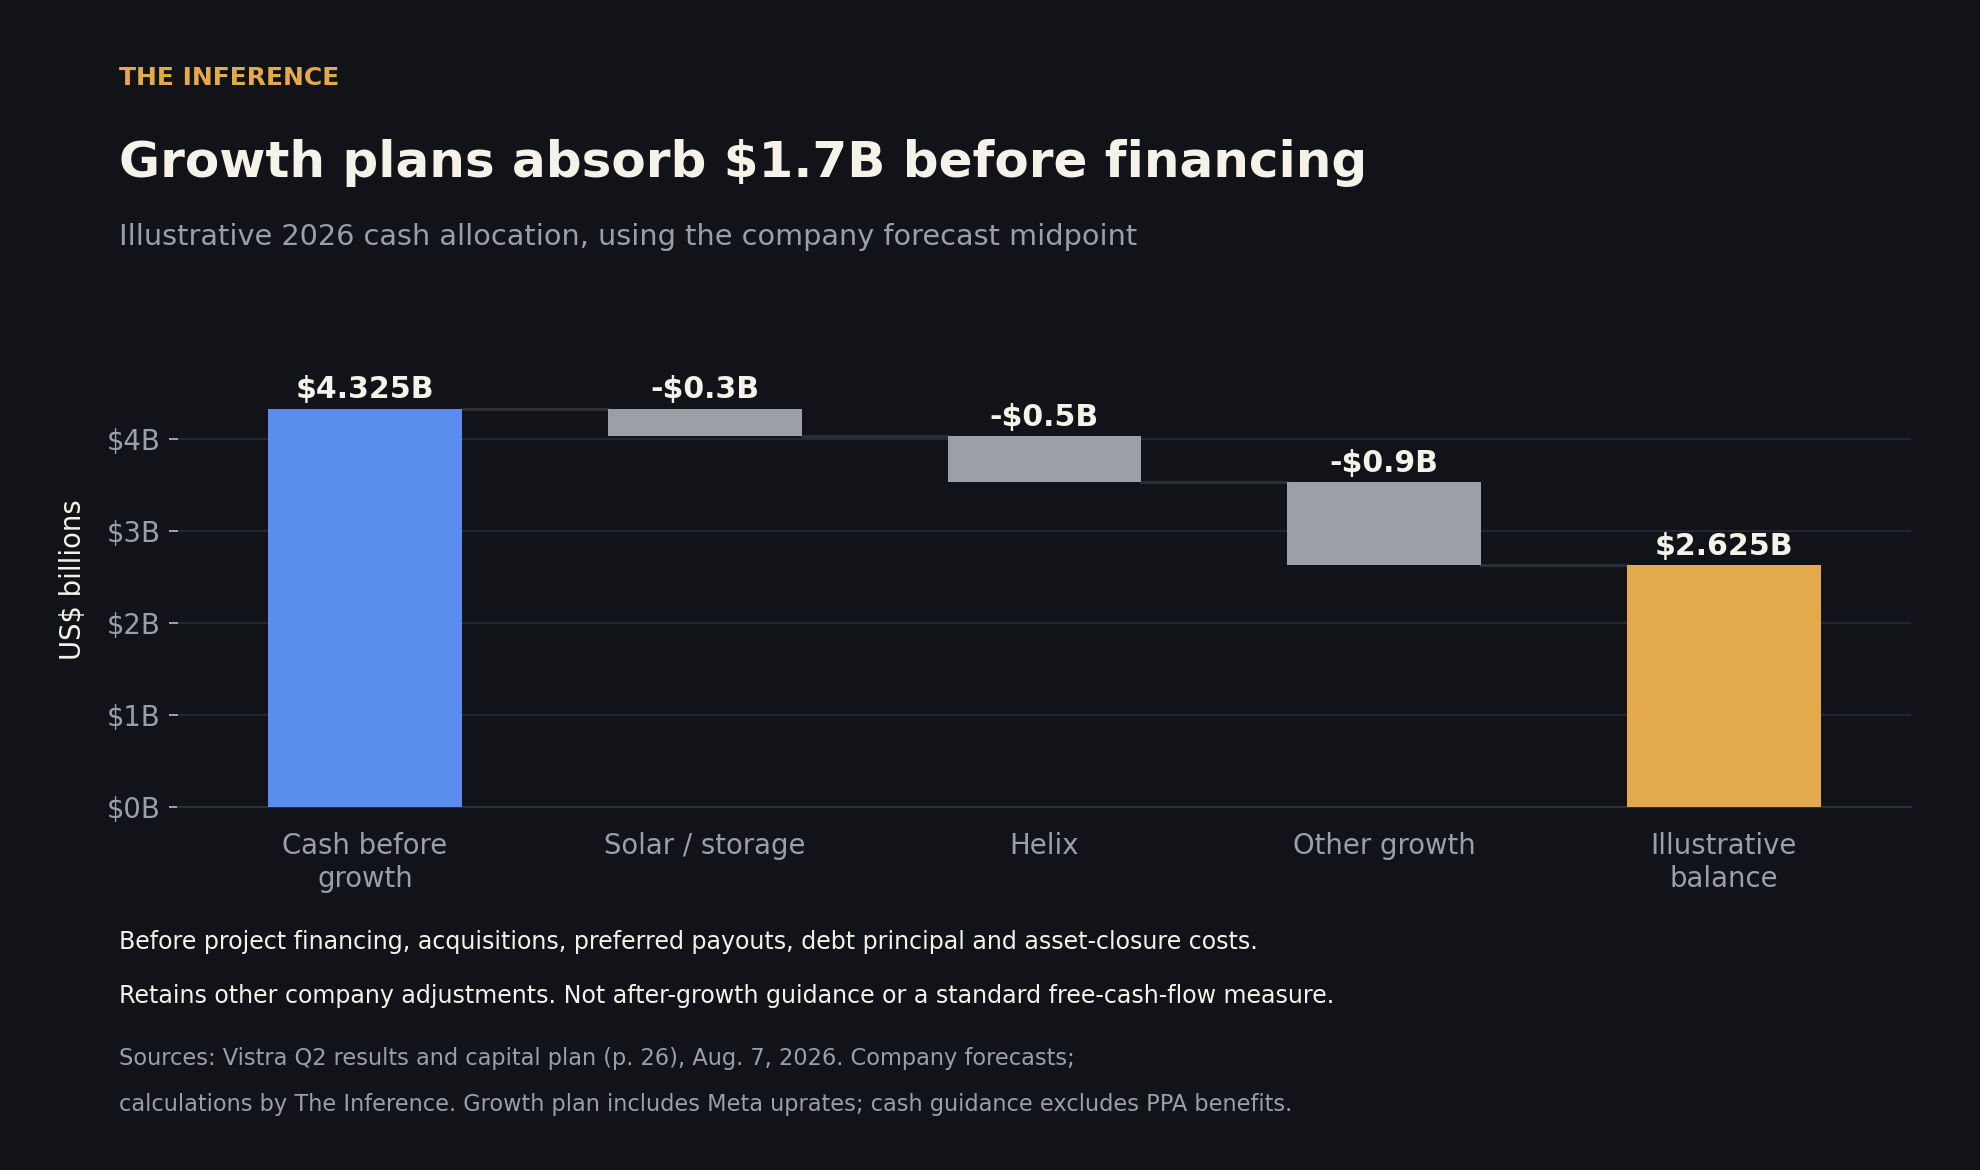
Vistra's August plan budgets approximately $300 million for solar and storage development, $500 million for Helix and $900 million of other growth spending in 2026. Capital plan, page 26. Subtracting that budgeted gross growth spending leaves $2.625 billion, about 5.6% of the estimated equity value. This illustration excludes project financing, preferred payouts, debt principal, acquisition funding and asset-closure costs, retaining management's other cash-flow adjustments. It is neither after-growth guidance nor a standard free-cash-flow yield. The operating forecast excludes Meta and Cogentrix contributions, while the spending plan includes Meta uprate investment.
Scarcity creates bargaining power; capital allocation decides who keeps the benefit.
Helix is not yet a purchase order
Growth spending can create value. Financing can reduce the immediate equity contribution. Neither makes the investment free. Borrowing moves part of the burden into future debt service; retaining cash asks shareholders to wait for returns. The correct test is whether the completed investments generate enough additional cash per share to compensate for that delay and risk.
Helix makes the test concrete. At June 30, Vistra's initial $500 million remained callable and milestones for its second $500 million had not been met. Vistra may elect to fund the second amount anyway. It does not control the fund. Preferred-supplier status alone is not a purchase order.3
The strategic logic is credible: help assemble financing, infrastructure and customers, then sell power into projects that might otherwise stall. The downside is correlated exposure. If projects disappoint, Vistra could face weaker prospective power demand alongside weaker investment returns. Helix exchanges some of the simplicity of owning existing plants for a chance to capture more of the customer's spending.
The pending Cogentrix acquisition adds another allocation decision: approximately $2.3 billion in cash, five million shares and $1.5 billion of assumed debt for existing gas plants. Buying those plants expands Vistra's fleet without creating equivalent new supply for the grid. Shareholders need the acquisition's cash contribution to justify its funding and dilution.11
The September 10 financing announcement also deserves precision. Vistra priced $1.5 billion of junior notes with initial coupons of 7% and 7.25%, partly to redeem existing preferred stock. This is capital restructuring, not a disclosed $1.5 billion AI construction budget. Its net cost depends on which preferred payments disappear.12
The grid is pushing back
The strongest challenge to the bullish case comes from the grid itself. PJM's July auction for the 2028/29 delivery year secured less capacity than its reliability requirement, yet the clearing price was capped at $325 per megawatt-day, below the previous auction. Capacity payments compensate resources for availability; they are separate from electricity sales. Scarcity can persist while regulators constrain one route through which generators monetize it.13
Texas supplies another warning. Governor Greg Abbott's August 3 directive required verification and an audit before data centers in ERCOT's interconnection process advance. ERCOT had already cautioned that its preliminary long-term forecast exceeded expected demand growth. Proposed megawatts are an opportunity pipeline whose conversion depends on permission, financing and actual customers.14,15
This scrutiny reaches the economics of individual projects. FERC is examining how large loads connect without shifting their costs onto other customers. PJM's independent market monitor has argued for enforceable curtailment obligations while data centers arrange new generation. These are evolving rules and contested proposals, not settled outcomes. For prospective Helix projects, connection costs and curtailment rules can affect both investment returns and the electricity Vistra ultimately sells.16,17
What to watch next
The bullish case survives a smaller demand pipeline. EIA's September outlook still forecasts roughly 2% annual electricity-sales growth in 2026 and 2027, even while acknowledging the Texas pause. It also expects rapid solar growth. The opportunity therefore depends on location, hour and dependable supply, rather than electricity demand alone. Existing plants can remain valuable even when many proposed data centers never open.18
Vistra has a credible operating advantage, but the headline cash yield overstates the simplicity of owning it. The existing fleet and signed contracts are worth valuing first, against evidence that new investment improves cash generation per share. The decisive disclosures are Helix's power contracts and capital calls, Meta's delivery milestones, the pending Cogentrix acquisition's financing, and cash remaining after growth investment. Burke's next allocation of shareholder money will tell us more than another estimate of AI's electricity appetite.
Get Power by email, free
How AI's hunger for electricity moves utilities, power plants and the grid. In our daily email, every weekday.