Meta Buys Williams Power; Blackstone's $5.34 Billion Builds It
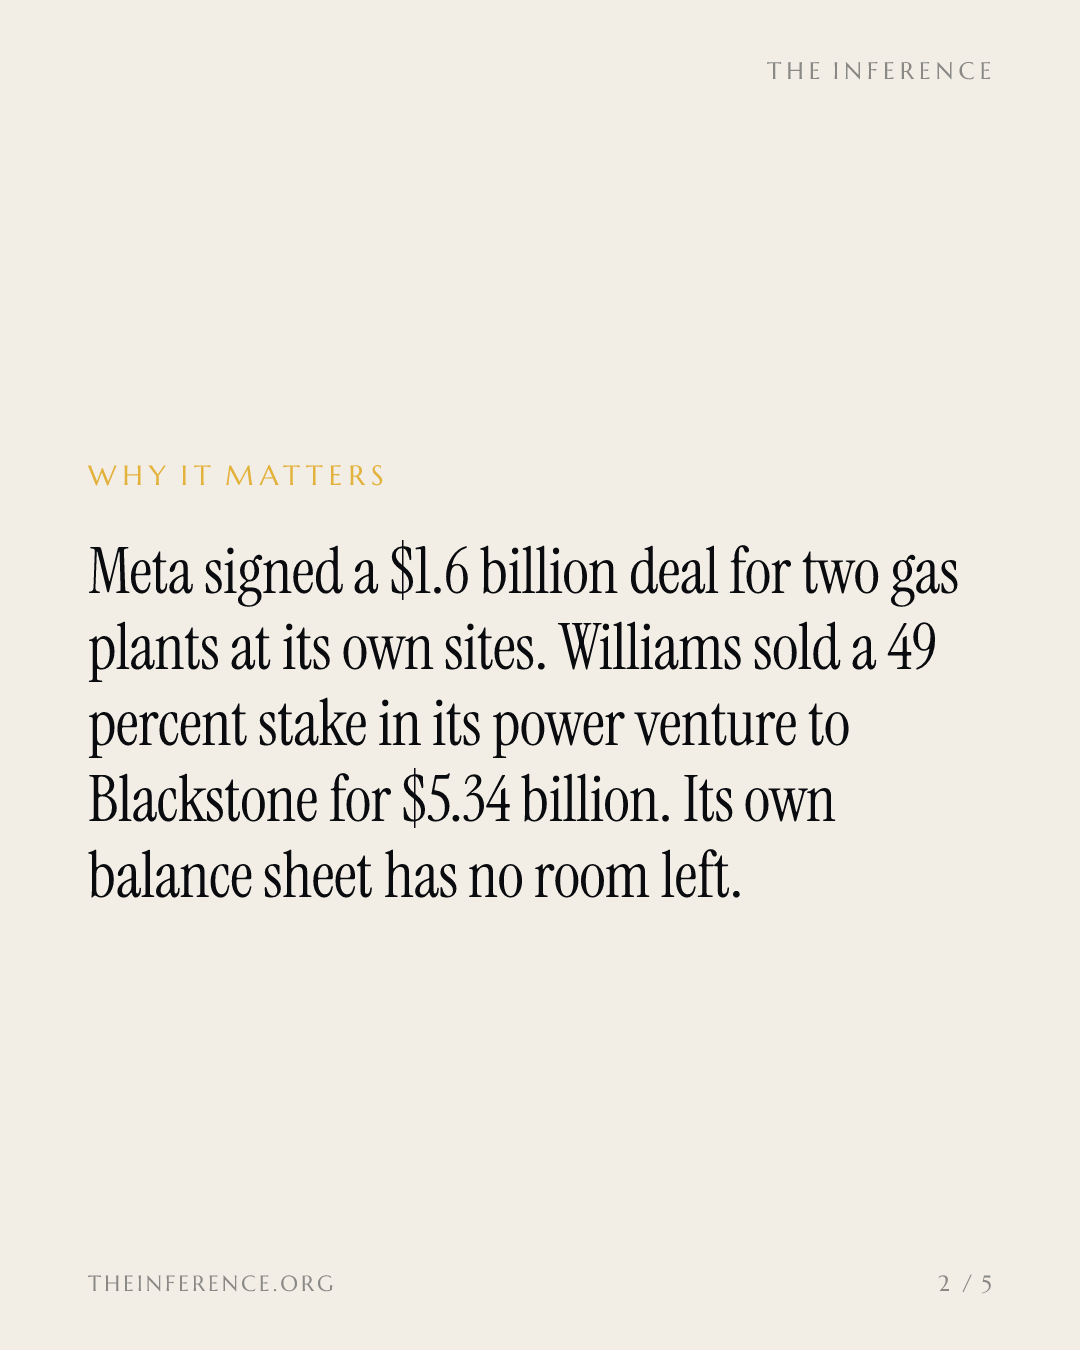
Barron's named Meta on November 3 as the buyer of 400 megawatts of behind-the-meter gas power from Williams. The plants are financed with $5.34 billion of Blackstone-led capital because Williams' leverage, at 3.80 times, already sits under a four-times ceiling that now governs executive pay.
 Vincent Jiang · 3 min read
Meta is the name on the 400 megawatts
Williams−6.63% — Williams, down 6.63 percent today, the Oklahoma-based natural gas pipeline operator that delivers about a third of the country's gas 1, has a named customer for its power business. Barron's reported on November 3 that Meta+1.50% — Meta, up 1.50 percent today holds a $1.6 billion deal with Williams for two behind-the-meter gas plants, generation built at the customer's own site, totaling 400 megawatts, and that chief executive Chad Zamarin credited the project, which Williams calls Socrates, for his confidence in the full-year outlook 25.
The quarter backs him: adjusted EBITDA, Williams' core profit measure, of $2.039 billion, up 6 percent, tracking the upper half of the $8.3 billion to $8.5 billion range, with Socrates fully online ahead of schedule and a second plant, Plato North, due by mid-November 1. One or two more power projects will be announced before year end, management told analysts 3.
This follows The Inference's November 3 account of the $1.9 billion Williams share block and its October 13 piece on Meta's AI finances. New this week are the customer's name, the partner-payment schedule in the 10-Q, and executive pay tied to the leverage ceiling.
The construction money is private equity's
Outside capital funds about half the build. In July, Williams sold a 49 percent noncontrolling stake in Pantheon, the venture holding its five power projects, for $5.34 billion of committed capital from funds managed by Blackstone+6.18% — Blackstone, up 6.18 percent today Credit & Insurance, with Apollo and KKR alongside 45. Of that, $4.4 billion covers 49 percent of expected growth capex and about $0.9 billion is extra consideration paid to Williams 4. The cash lands in stages: $3.74 billion in July, $1 billion in October, the rest through the first quarter of 2027, all dedicated to construction 4.
The structure exists because the balance sheet has little room. Leverage was 3.80 times adjusted EBITDA at September 30 1, and the new pay framework ties a 10 to 16 percent EBITDA growth target through 2030 to staying at or below four times 3.
Williams' own deal announcement says the partnership lets it keep growing "without stretching corporate leverage," inside a 3.5 to 4.0 times target 5. The 10-Q also carries a $1.6 billion working capital deficit and $2.2 billion of debt due within a year 4. Capex has outrun operating cash flow in three of the past four quarters, and the third-quarter gap was just over $1 billion 6.
Capex has outrun operating cash flow in three of the past four quarters
Third-quarter capex ran $1.0 billion ahead of operating cash flow
- Capital expenditure
- Operating cash flow
Data
| Capital expenditure | Operating cash flow | |
|---|---|---|
| Q4 '23 | $0.69B | $1.81B |
| Q1 '24 | $0.54B | $1.23B |
| Q2 '24 | $0.61B | $1.28B |
| Q3 '24 | $0.73B | $1.24B |
| Q4 '24 | $0.8B | $1.22B |
| Q1 '25 | $1.01B | $1.43B |
| Q2 '25 | $1.01B | $1.45B |
| Q3 '25 | $0.99B | $1.44B |
| Q4 '25 | $1.98B | $1.58B |
| Q1 '26 | $0.99B | $1.6B |
| Q2 '26 | $1.86B | $1.38B |
| Q3 '26 | $2.51B | $1.51B |
Shareholders are paying 2028 prices
The bill arrives before the earnings. The stock trades at 28.4 times trailing earnings against a five-year median of 24.7 7, about 26 times enterprise value to this year's guidance midpoint on AInvest's arithmetic 8, on a free cash flow yield of minus 0.2 percent 7. Insiders sold $11.1 million of stock over twelve months and bought none; the general counsel sold 2,000 shares at $74.17 on November 2 under a selling plan dated September 2025 79.
The bull case is real: dividend coverage of 2.42 times 1, a promote structure that improves Williams' economics as the plants perform, and a buyback right on the partner stake between years seven and fourteen 5. None of that brings the 2028 earnings forward 83. The EBITDA that would justify the multiple is scheduled to inflect in 2028 and beyond 8, while $5.9 billion of long-lead power equipment is already committed 3.
The tells are the leverage ratio printed when the next projects are sanctioned, and whether the new contracts are firm and of Socrates's length, an initial ten years 4. Until then, Williams sells the power to Meta and the construction risk to Blackstone.
Get Power by email, free
How AI's hunger for electricity moves utilities, power plants and the grid. In our daily email, every weekday.