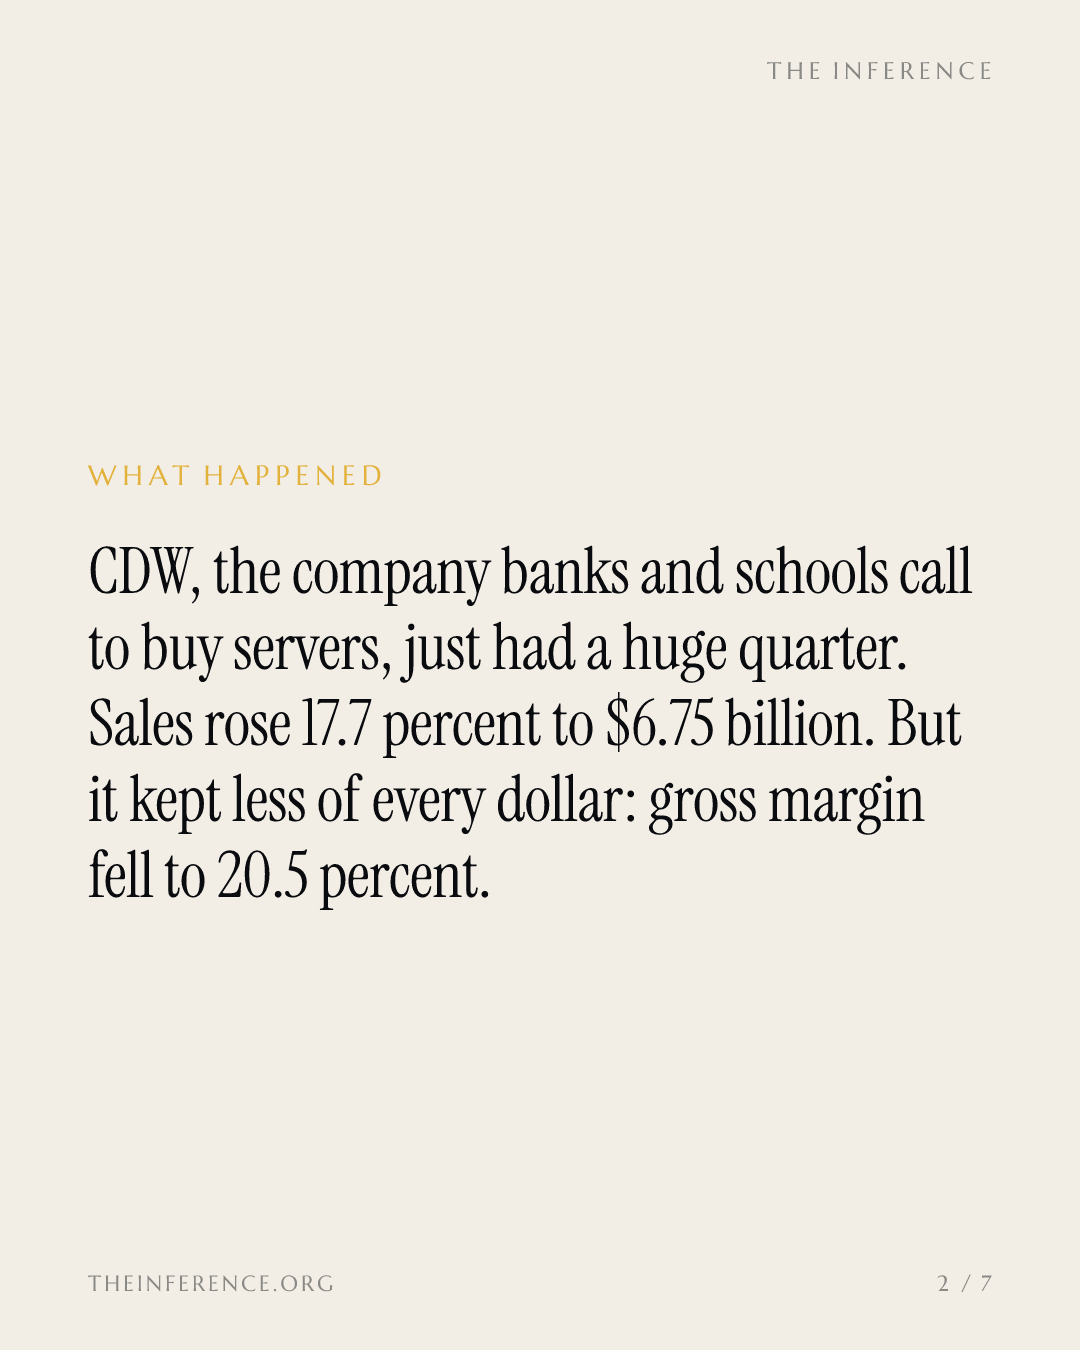
CDW grew sales 17.7%, but gross margin fell 140 basis points to 20.5% as hardware mix grew
CDW's third quarter filed November 4 shows enterprise AI hardware moving through the reseller at full speed and at a thinner cut: sales up 17.7 percent, gross margin down 140 basis points, and per-share earnings made below the gross profit line.
 Vincent Jiang · 3 min read
Servers moved the tollbooth's traffic, and it took a thinner cut
CDW Corporation+14.32% — CDW Corporation, up 14.32 percent today, the Vernon Hills, Illinois company most American banks, schools and agencies call when they buy servers and storage, filed its third-quarter 8-K at 7:00 a.m 23. ET on November 4 and the market read it in minutes: shares opened up more than 6 percent 23. Chief executive Christine Leahy called the quarter "powered by broad-based strength across our diverse customer end-markets and strong momentum in enterprise AI adoption" 2. Banks led the stampede: net sales to financial services customers rose 73.2 percent, to $571.5 million 1.
More traffic, thinner toll
Here is the part the release buries in a footnote. Net sales grew 17.7 percent to $6,754.5 million, but gross profit grew only 10.3 percent, to $1,385.3 million, and gross margin fell to 20.5 percent from 21.9 percent a year ago 1.
Gross margin has slid about two points since early 2024 as hardware took over growth
Data
| Gross margin | |
|---|---|
| Q1 '24 | 21.8% |
| Q2 '24 | 21.8% |
| Q3 '24 | 21.8% |
| Q4 '24 | 22.3% |
| Q1 '25 | 21.6% |
| Q2 '25 | 20.8% |
| Q3 '25 | 21.9% |
| Q4 '25 | 22.8% |
| Q1 '26 | 21% |
| Q2 '26 | 20.1% |
| Q3 '26 | 20.5% |
The stated cause is "mix into and lower margin in certain product categories," unnamed. The categories named as growth drivers are data storage and servers, notebooks and software 1, and servers and storage are the thin-spread goods a reseller moves; software is where a reseller keeps the spread. Growth concentrated where the toll is lowest.
Revenue growth accelerated through 2026, reaching $6.75 billion in Q3
Data
| Net sales | |
|---|---|
| Q1 '24 | $4.87B |
| Q2 '24 | $5.42B |
| Q3 '24 | $5.52B |
| Q4 '24 | $5.19B |
| Q1 '25 | $5.2B |
| Q2 '25 | $5.98B |
| Q3 '25 | $5.74B |
| Q4 '25 | $5.51B |
| Q1 '26 | $5.68B |
| Q2 '26 | $6.57B |
| Q3 '26 | $6.75B |
The per-share show
The quarter still beat: non-GAAP earnings of $3.26 against a Zacks consensus of $2.92, on revenue of $6.75 billion against $6.12 billion expected 3.
But look below the gross profit line. Operating income rose 10.4 percent to $489.5 million, while non-GAAP operating margin held flat at 9.2 percent 16. Selling and administrative expenses rose 10.3 percent to $896 million, including the first quarter carrying the $525 million Lovelytics acquisition, a data and AI services firm CDW closed in September 17.
Net interest expense rose 19.8 percent to $66 million on higher revolver borrowings, and inventory is stocked: $1,019.9 million on the balance sheet, up from $504.7 million a year ago, with days of supply at 18 versus 11 18. Weighted-average diluted shares fell to 126 million from 132 million 1. The board raised the dividend about 8 percent to $0.680 4. Add the buyback and per-share growth does much of the work.
What the bulls say
Fiduciary Management, a Milwaukee money manager, argues in its Q3 letter that the market misreads CDW: "the buildout of AI-ready infrastructure, the modernization of legacy data environments, and the general increase in IT activity required to support these initiatives should all flow through as incremental opportunity" 5. The $525 million Lovelytics purchase is the bet that services carry the margin hardware does not 7. Fair. But this quarter shows the sequence: hardware first, margin later.
Watch the 20.5 percent, not the top line
CDW never says how much of the quarter is AI 1. The number that will tell whether the services thesis arrives is the gross margin line in the next two prints. If AI traffic keeps growing while the rate holds at 20.5 percent or slips, CDW is a tollbooth taking more cars at a lower price 1. Deep dive in the sources below.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.