WhiteFiber's $865 million lease is signed; delivering it is what the market doubts
WhiteFiber closed a $60 million land purchase the same week it admitted switchgear problems have delayed billing at its first North Carolina data hall and its project financing still is not signed. The $865 million lease proves the demand; the open question is delivery.
 Richard Tang · 4 min read
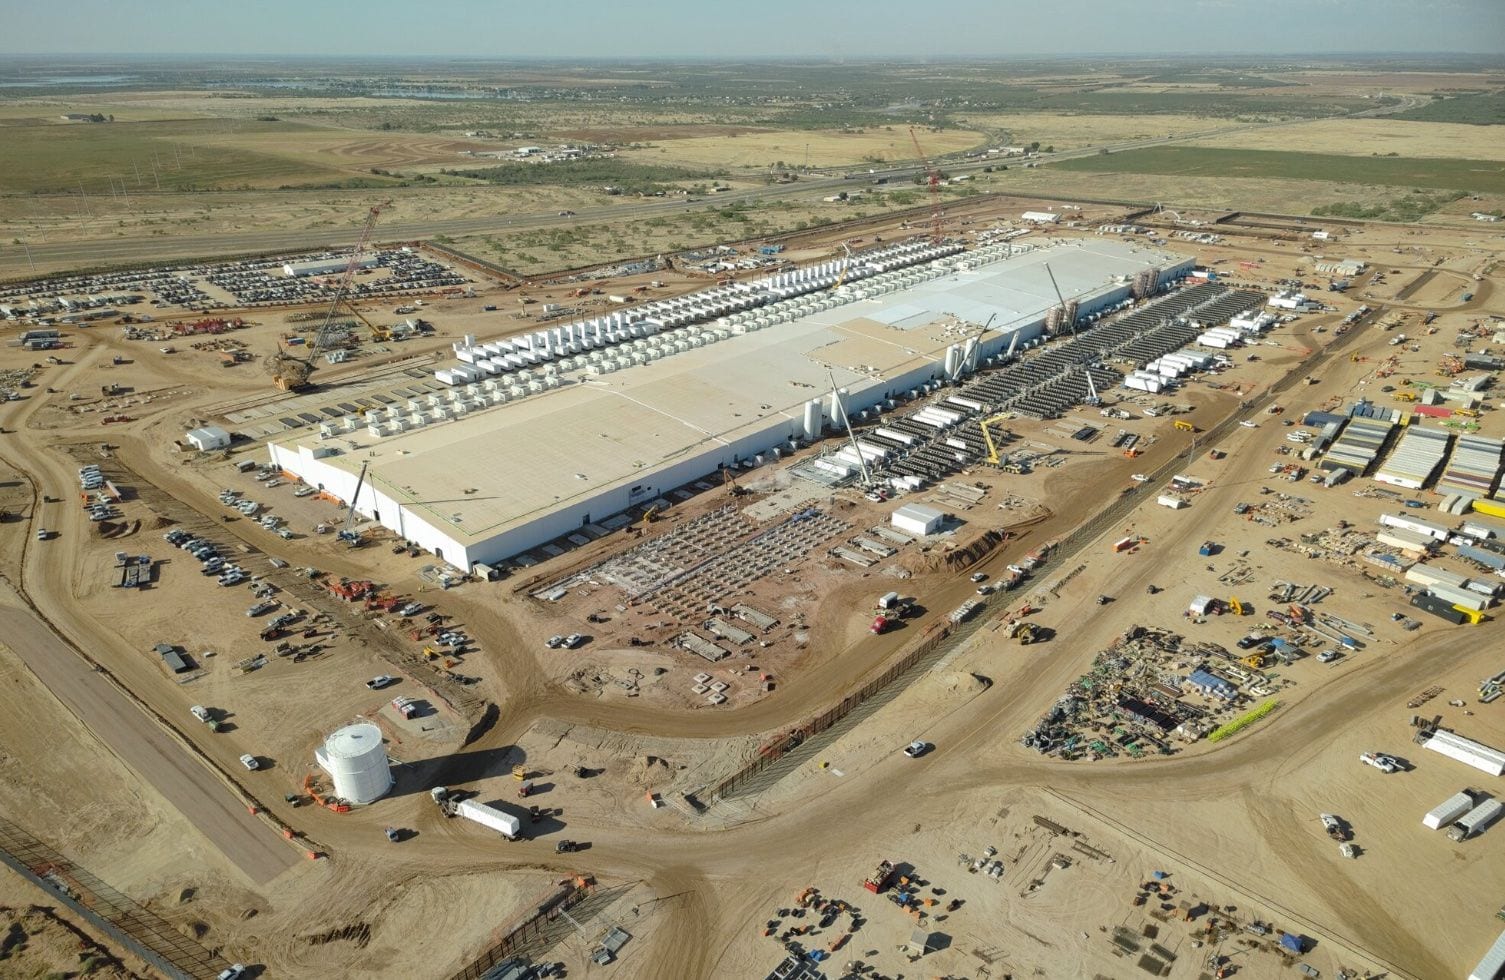
The 8-K WhiteFiber filed on November 3 does two things at once, and the gap between them is the story 1. It completes a $60 million cash purchase of two Yadkin County, North Carolina, sites meant for the company's next data center campuses, and it discloses that switchgear problems during commissioning interrupted service and billing on the first 20 megawatts at its existing NC-1 campus, pushing full run-rate billing past the August target 1.
Needham's estimate cut, dated October 27, put dollars on that slip, and the analyst still rates the stock a Buy 2. Shares still trade near $10, close to the 52-week low 5. The market is not doubting AI demand; it is doubting that this company turns a signed lease into billed revenue on schedule.
The lease is real; the ramp is the problem
The commercial side works. Nscale, the tenant at NC-1 in Madison, North Carolina, holds a ten-year lease covering 40 megawatts of critical IT load, worth about $865 million with annual escalators, and Needham describes the offtake as backed by an investment-grade hyperscaler 2. That is the demand signal the whole AI infrastructure trade rests on, and WhiteFiber−10.77% — WhiteFiber, down 10.77 percent today has it in hand 2.
The physical side is where it strains. Switchgear, the equipment that distributes and protects electrical power inside a facility, failed during commissioning and cut off billing on the first 20 MW data hall 1. About 35 of the contracted 40 megawatts run today, with the rest to follow 1. Needham cut its third-quarter colocation forecast to $14.0 million from $26.3 million and trimmed full-year 2026 EBITDA to $61.0 million 2, and the NC-1 project financing with a prospective lending group is still being documented, with no assurance it closes 1.
Needham cut every forecast the NC-1 billing delay touches
Every line the NC-1 ramp touches came down; the 2027 model did not move
- Needham prior
- Needham revised
- Estimate
Data
| Needham prior | Needham revised | |
|---|---|---|
| Q3 colo revenue (estimate) | $26.3M | $14M |
| Q3 EBITDA (estimate) | $23.2M | $13.5M |
| 2026 revenue (estimate) | $159.8M | $147.2M |
| 2026 EBITDA (estimate) | $71M | $61M |
Analyst models bill the contract, not the hall
Needham left its 2027 model untouched and hangs the $41 target on it; the consensus target across the covering analysts is $38 5. Needham, one of the underwriters of WhiteFiber's 2025 IPO 5, is arguing the delivery gap closes, while more than 12% of the float sold short 5 argues it does not.
Seeking Alpha's Dorine Cherop holds the stock at Hold for the same structural reason: converting backlog into recurring, high-margin revenue is unproven, and heavy investment outpaces operating cash flow until permanent financing lands 4. Both sides agree the demand exists. They disagree on whether this operator reaches full billing on time.
The next campuses are bought before they are leased
The company closed the purchase of NC-2 and NC-3 on October 28, two sites with a minimum of 60 MW of initial capacity, with a possible 198 MW within seven years, subject to confirmation and power availability 1. Customer support is early-stage: non-binding letters of intent, some from investment-grade counterparties, cover the new sites and NC-1 expansion, and no tenant is named 1.
Two thirds of the campus pipeline is bought, not yet billed
Data
| Value | |
|---|---|
| NC-1 running | 35 |
| NC-1 contracted | 40 |
| NC-2/3 initial | 60 |
| NC-2/3 possible | 198 |
WFAE reported in August that Yadkin County had approved a two-year moratorium on data center development, and the company's filing does not address it 3. The seller, Unifi Manufacturing, stays on parts of the property under a partial leaseback that offsets carrying costs 1. Management says development spending will align with definitive customer agreements and financing 1; that promise is now the thing to test.
What decides the stock now
Third-quarter results arrive on November 10 1. Three tests follow, each one a link in the chain from AI workload to billed revenue: the remaining 5 MW at NC-1, a signed financing, and letters of intent that become leases 1. Retail holders on Stocktwits treat the stock as a two- to three-year bet that all three campuses reach full capacity 6; the filing shows why every link between here and there can slip 1.
The demand side of the AI buildout is no longer the question; an $865 million lease and investment-grade letters of intent settle it 21. What decides returns is the unglamorous middle of the chain: equipment that commissions on time, lenders who sign, counties that permit. Anyone learning AI today should study that middle, not just the models, because making capacity billable is where this industry's value is being decided.
The reward belongs to whichever operator delivers it on schedule, and as of this week the record at WhiteFiber says that operator is still working on it.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.