S&P gave Equinix's new bonds a 6.5x downgrade trigger; its shareholders face 5x and election risk
On November 3 S&P rated the new notes BBB+ with a 6.5x downgrade trigger, and the same night three data-center states elected governors who want conditions on new builds. The debt holds a covenant-shaped cushion; the equity holds the timetable.
 Vincent Jiang · 3 min read
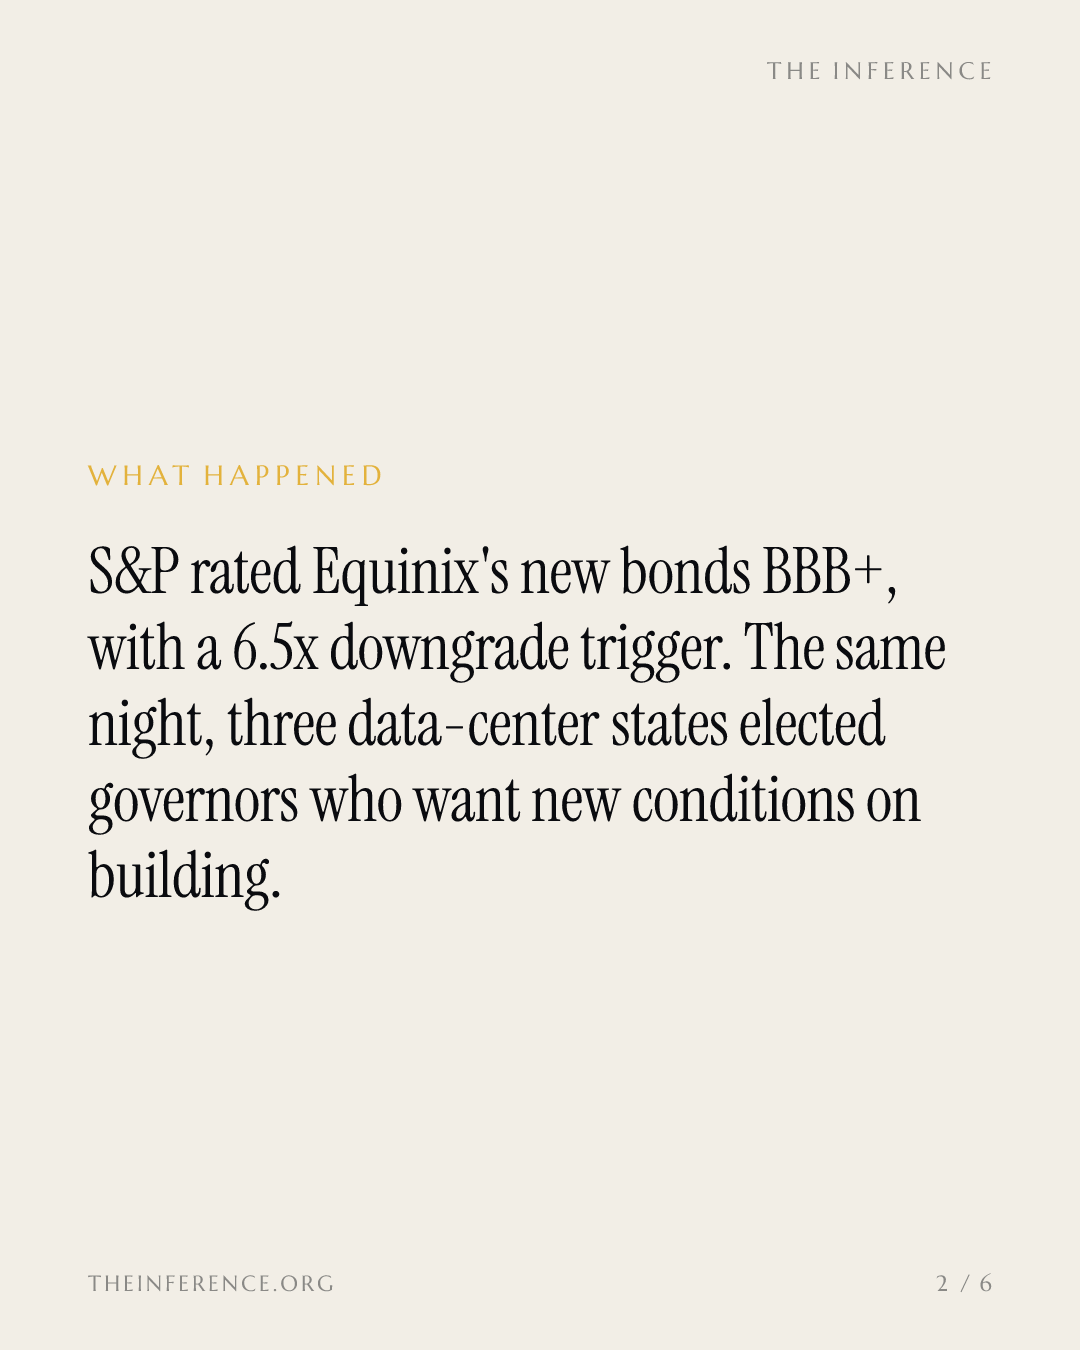
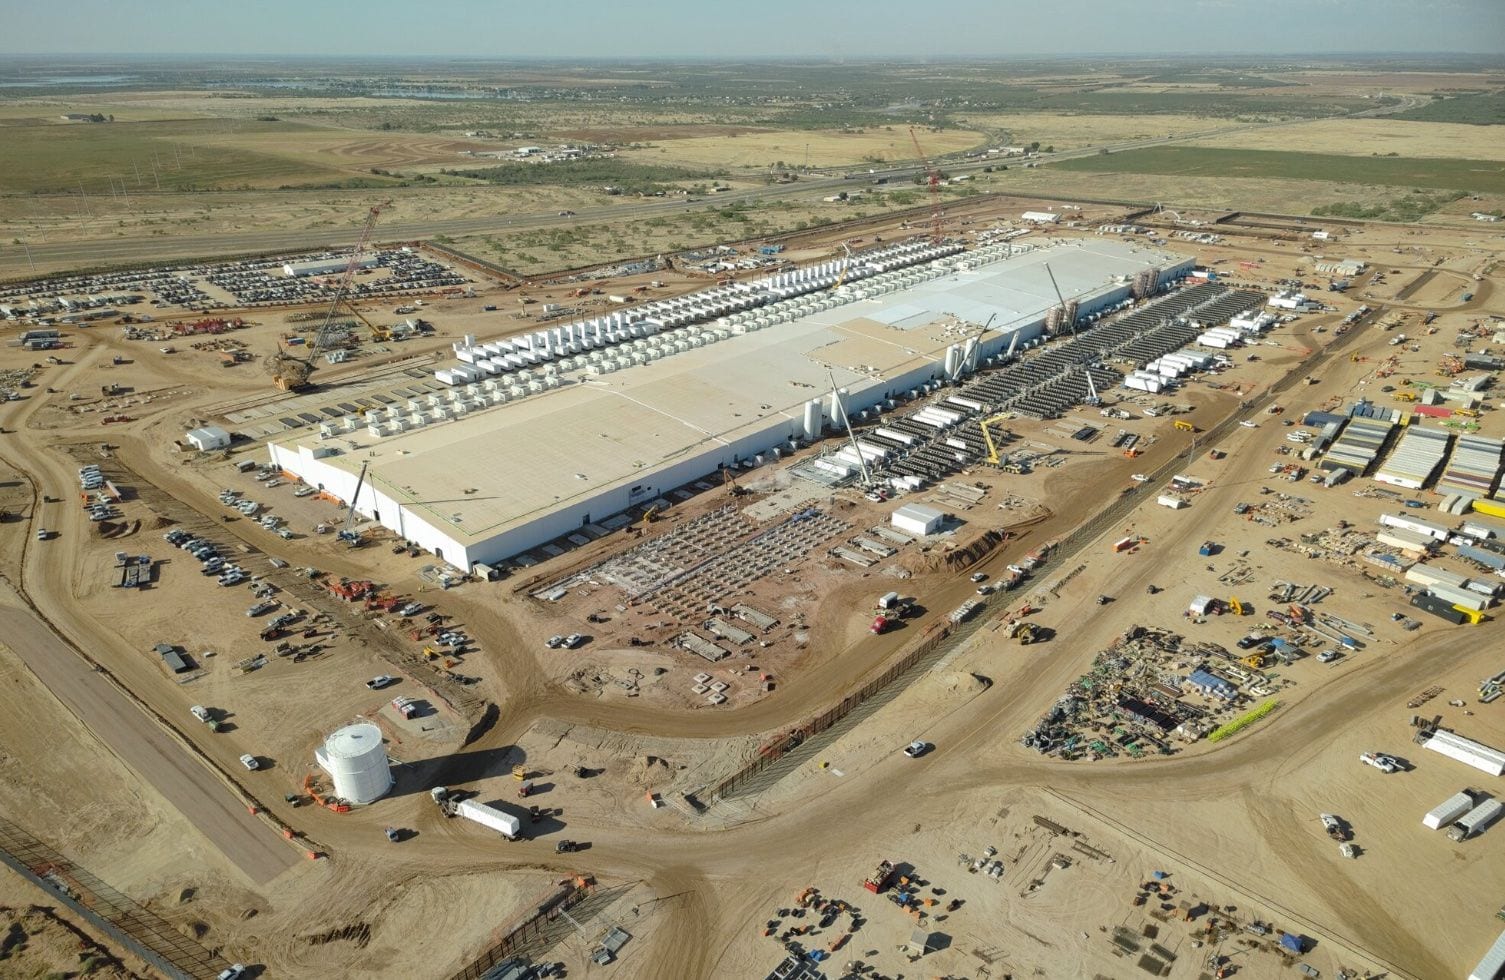
On November 3, S&P Global Ratings$123B — S&P Global Ratings, private, latest valuation $123B stamped 'BBB+' on Equinix's+1.96% — Equinix, up 1.96 percent today proposed senior unsecured notes, issued through its Equinix Europe 2 Financing subsidiary, and in the same report published the arithmetic of the deal: the build gets the money, the trigger comes later 1. Equinix, which owns 282 data centers across 77 metro areas where clouds and enterprises physically connect, plans to spend $5 billion to $7 billion a year on expansion through 2029 1.
That marks the second bite of leverage in a week. Our November 2 coverage showed the record bookings quarter was funded with $3.8 billion of new debt and a $2 billion stock shelf; what is new since is S&P's published leverage path, and an election night that moved the ground under the build 12.
The bond gets a trigger, the shareholder gets the timetable
S&P expects adjusted debt to EBITDA, about 4.0x today on roughly $23 billion of existing unsecured debt plus about $2 billion of finance leases, to reach about 5x in two to three years; the downgrade trigger sits at 6.5x 1.
Equinix's leverage climbs from 4x toward a 6.5x downgrade trigger
Leverage rises toward 5x while the rating holds under a 6.5x trigger
- Estimate
Data
| Value | |
|---|---|
| Now | 4 |
| In 2-3 yrs (estimate) | 5 |
| Trigger | 6.5 |
The bondholder's position is contractually ahead. S&P itself labels Equinix's development risk "significant but manageable": labor shortages, permitting delays, local moratoriums and supply chains, plus leases customers can terminate when delivery runs late 1.
Management's counter is yield, mid-20% on new projects and a 27% cash-on-cash yield on stabilized assets for the twelve months ended September 30, alongside revenue guidance raised to 10% to 13% growth a year through 2029, from 7% to 10% 1. S&P also flags the flip side of that growth thesis: AI inferencing demand carries "long-term uncertainty" on durability 1.
The ground under the build moved the same night
Texas, Ohio and Georgia each elected a Democratic governor on November 3 2. Texas's Gina Hinojosa wants an immediate halt to new projects and an end to tax breaks; Ohio's Amy Acton supports a moratorium outright 2.
Georgia is the least defined: no stated data-center platform was reported for winner Keisha Lance Bottoms, so the risk there reads, on the evidence available, as a possible rule rewrite rather than a freeze 2. The dollar exposure is concentrated: Texas alone holds about a quarter of US data center capacity due by 2030, per GLJ Research figures cited by Reuters 2.
Power risk becomes a customer contract, for what gets built
Equinix has already shown one way to survive that politics. Its Hampton, Georgia project signed a 20-year take-or-pay contract covering 100% of grid costs 2.
The mechanism matters for what it protects. Take-or-pay converts grid-cost exposure into a customer obligation, but only for capacity that actually gets built and delivered on time, so the equity eats both the political timetable and the cost of admission; the debt holds the trigger 12. For holders of either side of Equinix's capital structure, the bookings are the story everyone tells; the leverage path is the one that decides the rating, and it now has a dated route toward 5x 1.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.