S&P's Meta warning just landed on two LLCs holding $40 billion of AI data-center debt
Four days after S&P put Meta on a downgrade clock over $132 billion of projected cash deficits, the same negative outlook landed on Beignet and Sopaipilla, two Meta data-center financing vehicles carrying about $40 billion of debt. The warning is moving down the financing stack.
 Vincent Jiang · 3 min read
When a rating agency cuts the outlook on a $1.7 trillion company, the paperwork lands on companies most people have never heard of 1. On November 2, S&P Global Ratings$123B — S&P Global Ratings, private, latest valuation $123B revised the outlook on Beignet Investor LLC and Sopaipilla Investor LLC to negative from stable, "following similar action on Meta+2.23% — Meta, up 2.23 percent today Platforms Inc." 1 Neither vehicle employs anyone or sells anything. Both exist to hold debt that pays for Meta's AI data centers.
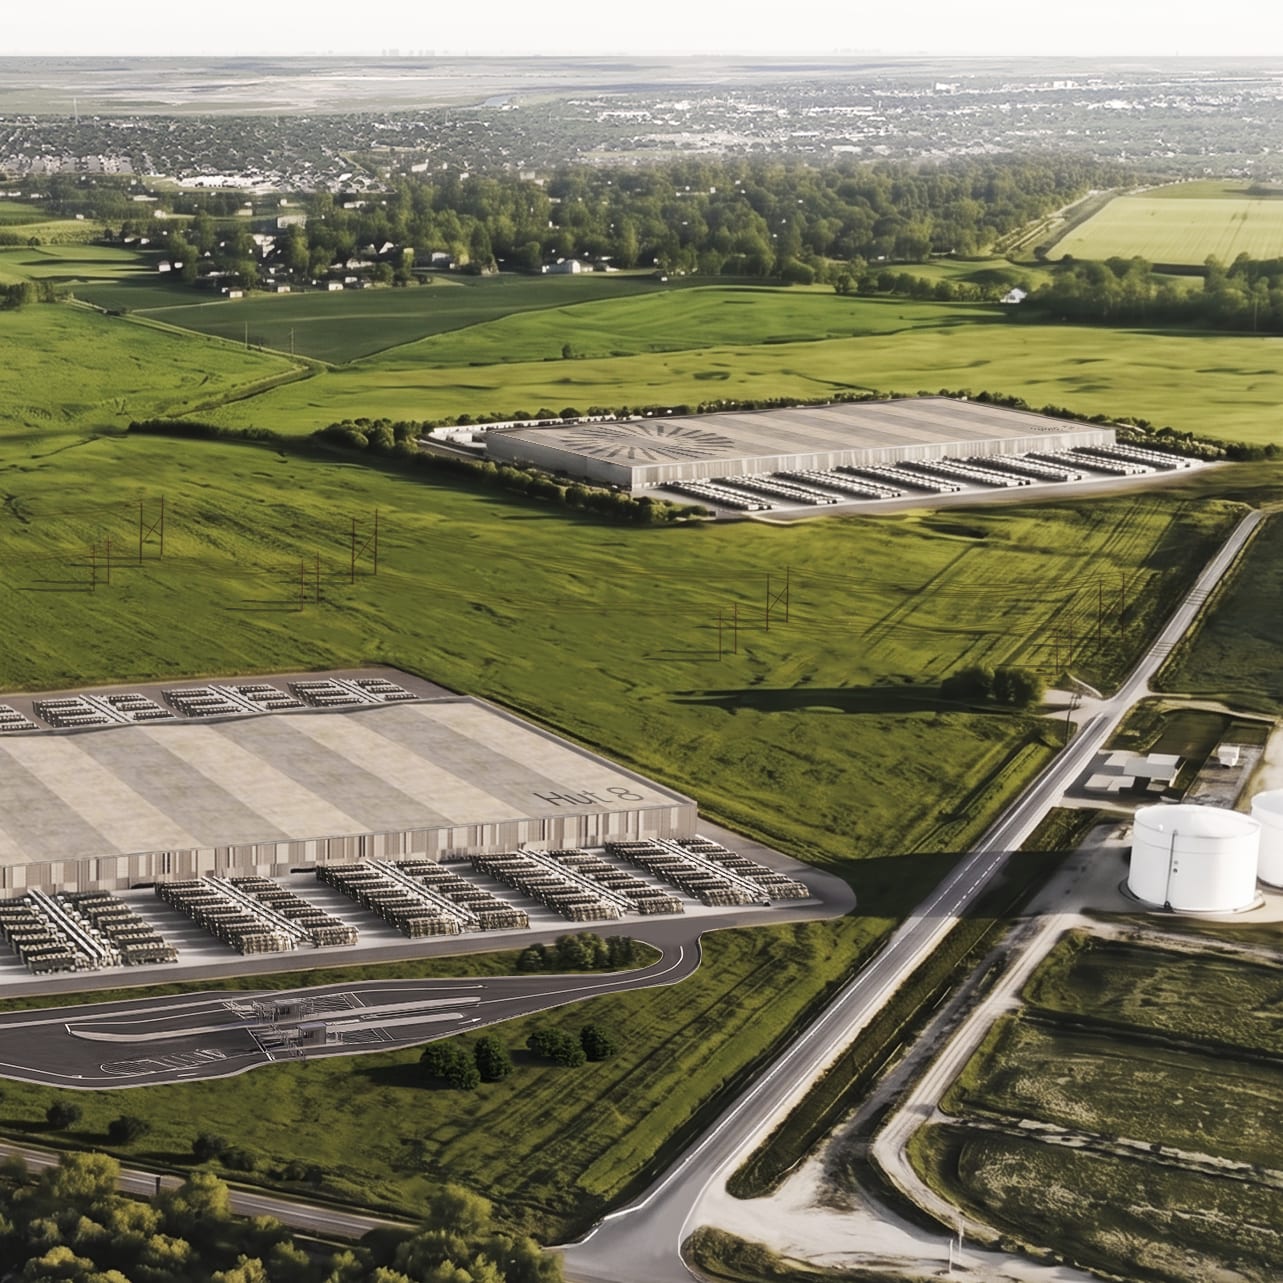
Beignet is the special-purpose entity behind Meta's Hyperion campus in Richland Parish, Louisiana: $27.3 billion of 6.581% notes due May 2049, arranged by Morgan Stanley−0.33% — Morgan Stanley, down 0.33 percent today, anchored by PIMCO, with a Blue Owl−2.07% — Blue Owl, down 2.07 percent today-led joint venture owning 80% and Meta 20% 5. Sopaipilla, created by BlackRock's−0.08% — BlackRock, down 0.08 percent today infrastructure units GIM and HPS, issued about $12.6 billion of notes due 2048 to fund an 80% stake in a joint venture building a 960-megawatt data center in El Paso, Texas 2.
Both carry S&P's 'A+' rating for one reason: Meta's contractual promises sit under them. That is why Meta's outlook is now theirs.
The anchor debt, $39.9 billion of it, moves with one rating
S&P cut Meta's outlook to negative on October 30, sizing free operating cash flow deficits at $132 billion across 2026 through 2028 and saying Meta's ability to monetize AI investments looks more limited than its peers' 3. Meta forecast capex of $135 billion to $145 billion next year after a third-quarter free cash flow deficit of $2.12 billion, and plans to sell up to $97.5 billion of stock to fund the build 3.
Wall Street's 59-analyst tally sees the three-year cash hole at $61.32 billion, less than half S&P's figure 4. The downgrade trigger is precise: leverage above 1.0x with cash flow still negative beyond 2028, a line Meta's leverage, up from 0.1x in 2025 largely through data-center leasing, could cross as early as 2027 3.
What the clock means for who holds the paper
S&P sizes Meta's three-year cash hole at more than double Wall Street's
- S&P forecast
- Wall Street consensus
- Estimate
Data
| S&P forecast | Wall Street consensus | |
|---|---|---|
| 2026 (estimate) | $22B | $9.55B |
| 2027 (estimate) | $71B | $43.32B |
| 2028 (estimate) | $39B | $8.45B |
The vehicles transmit the warning to bondholders directly. Beignet's notes already trade near 91.6 cents on the dollar, down from about 110 at issue, and bondholders are locked into 24-year paper while Meta's initial lease runs only four years, with exit rights from 2033 backstopped by a residual value guarantee 5.
A downgrade at Meta would push investment-grade-only mandates out of 'A+' paper that depends on Meta's credit, forcing selling at exactly the wrong moment. The market already prices the gap: five-year default insurance costs about 116 basis points for Meta against Microsoft's+1.83% — Microsoft, up 1.83 percent today 54 and Oracle's+5.11% — Oracle, up 5.11 percent today 275 4.
Default insurance prices Meta between Microsoft and Oracle
Data
| Five-year CDS spread | |
|---|---|
| Meta | 116 bps |
| Microsoft | 54 bps |
| Oracle | 275 bps |
Meta "respectfully disagrees" with S&P on monetization and points to its very strong credit profile 3. The disagreement settles on Meta's fourth-quarter call, where next year's capex guidance decides whose math was right 4. Watch the vehicle actions, not the headlines: when the anchor catches a negative outlook, every dollar built on it inherits the clock within days 1.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.