Hut 8 booked $189.5 million of profit on $413.8 million of bitcoin gains as revenue fell
Keefe Bruyette cut Hut 8's target to $92 from $154 on Monday, warning of an AI-lease drought into early 2027. The Q3 release counters on funding and dilution, with a $1.07 billion undrawn credit line and a completed bitcoin-funded buyback, while revenue keeps shrinking and profit still rides bitcoin's price.
 Vincent Jiang · 3 min read
Keefe Bruyette cut the target and warned of a lease drought
Hut 8−21.41% — Hut 8, down 21.41 percent today (Nasdaq: HUT), a bitcoin miner that now builds and leases out AI data centers, fell 14% on Monday November 2 after Keefe Bruyette analyst Stephen Glagola cut his price target to $92 from $154 1. The firm kept its Outperform rating but warned of a "lease catalyst drought" through early 2027: miners, it argued, already trade near the value of their signed leases 1. The stock closed at $55.01, then rebounded 16% to $63.62 on Tuesday ahead of the earnings report 2. Wednesday's third-quarter release lands as the company's reply.
The credit line is closed and the buyback is funded
Funding was answered before this week. In the second quarter Hut 8 closed $7.5 billion of investment-grade project bonds: $3.25 billion behind the River Bend campus in Louisiana at 6.192%, due 2042, and $4.25 billion behind Beacon Point Phase 1 in Texas at 6.129%, priced 20 basis points tighter 34. Both are non-recourse to the parent, meaning bondholders can claim only the project's cash flows, not the parent company's 3.
September added a $1.07 billion, four-year senior secured revolving credit facility led by JPMorgan with a twelve-bank syndicate, undrawn at quarter-end 56. Dilution was answered with bitcoin: Hut 8 repurchased $74.7 million of stock in the quarter and $175.3 million after it, funding the full $250 million program by selling roughly 3,100 coins, and the board raised the authorization to $1.0 billion on November 2 6.
The lease headline predates the downgrade; the pipeline is new
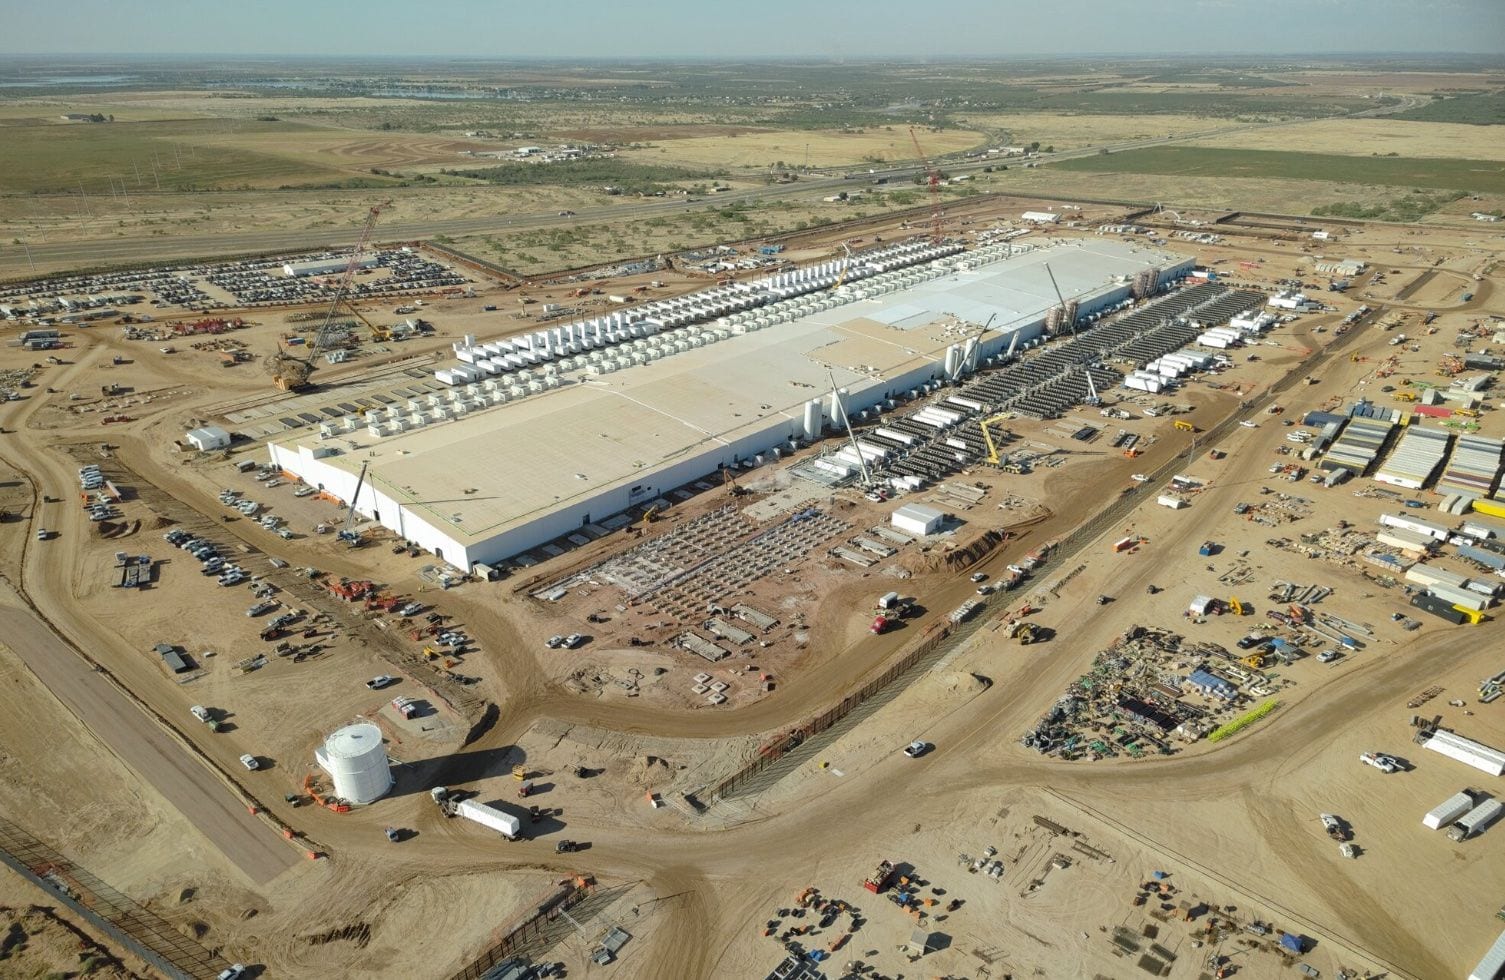
The quarter's lease headline is a second 352 MW lease at Beacon Point, the Texas campus: about $9.8 billion of expected contract value over its 15-year base term and roughly $655 million a year of expected net operating income, on take-or-pay terms, so rent is owed whether or not the tenant draws the power 67. That signing came in July, before the downgrade 7.
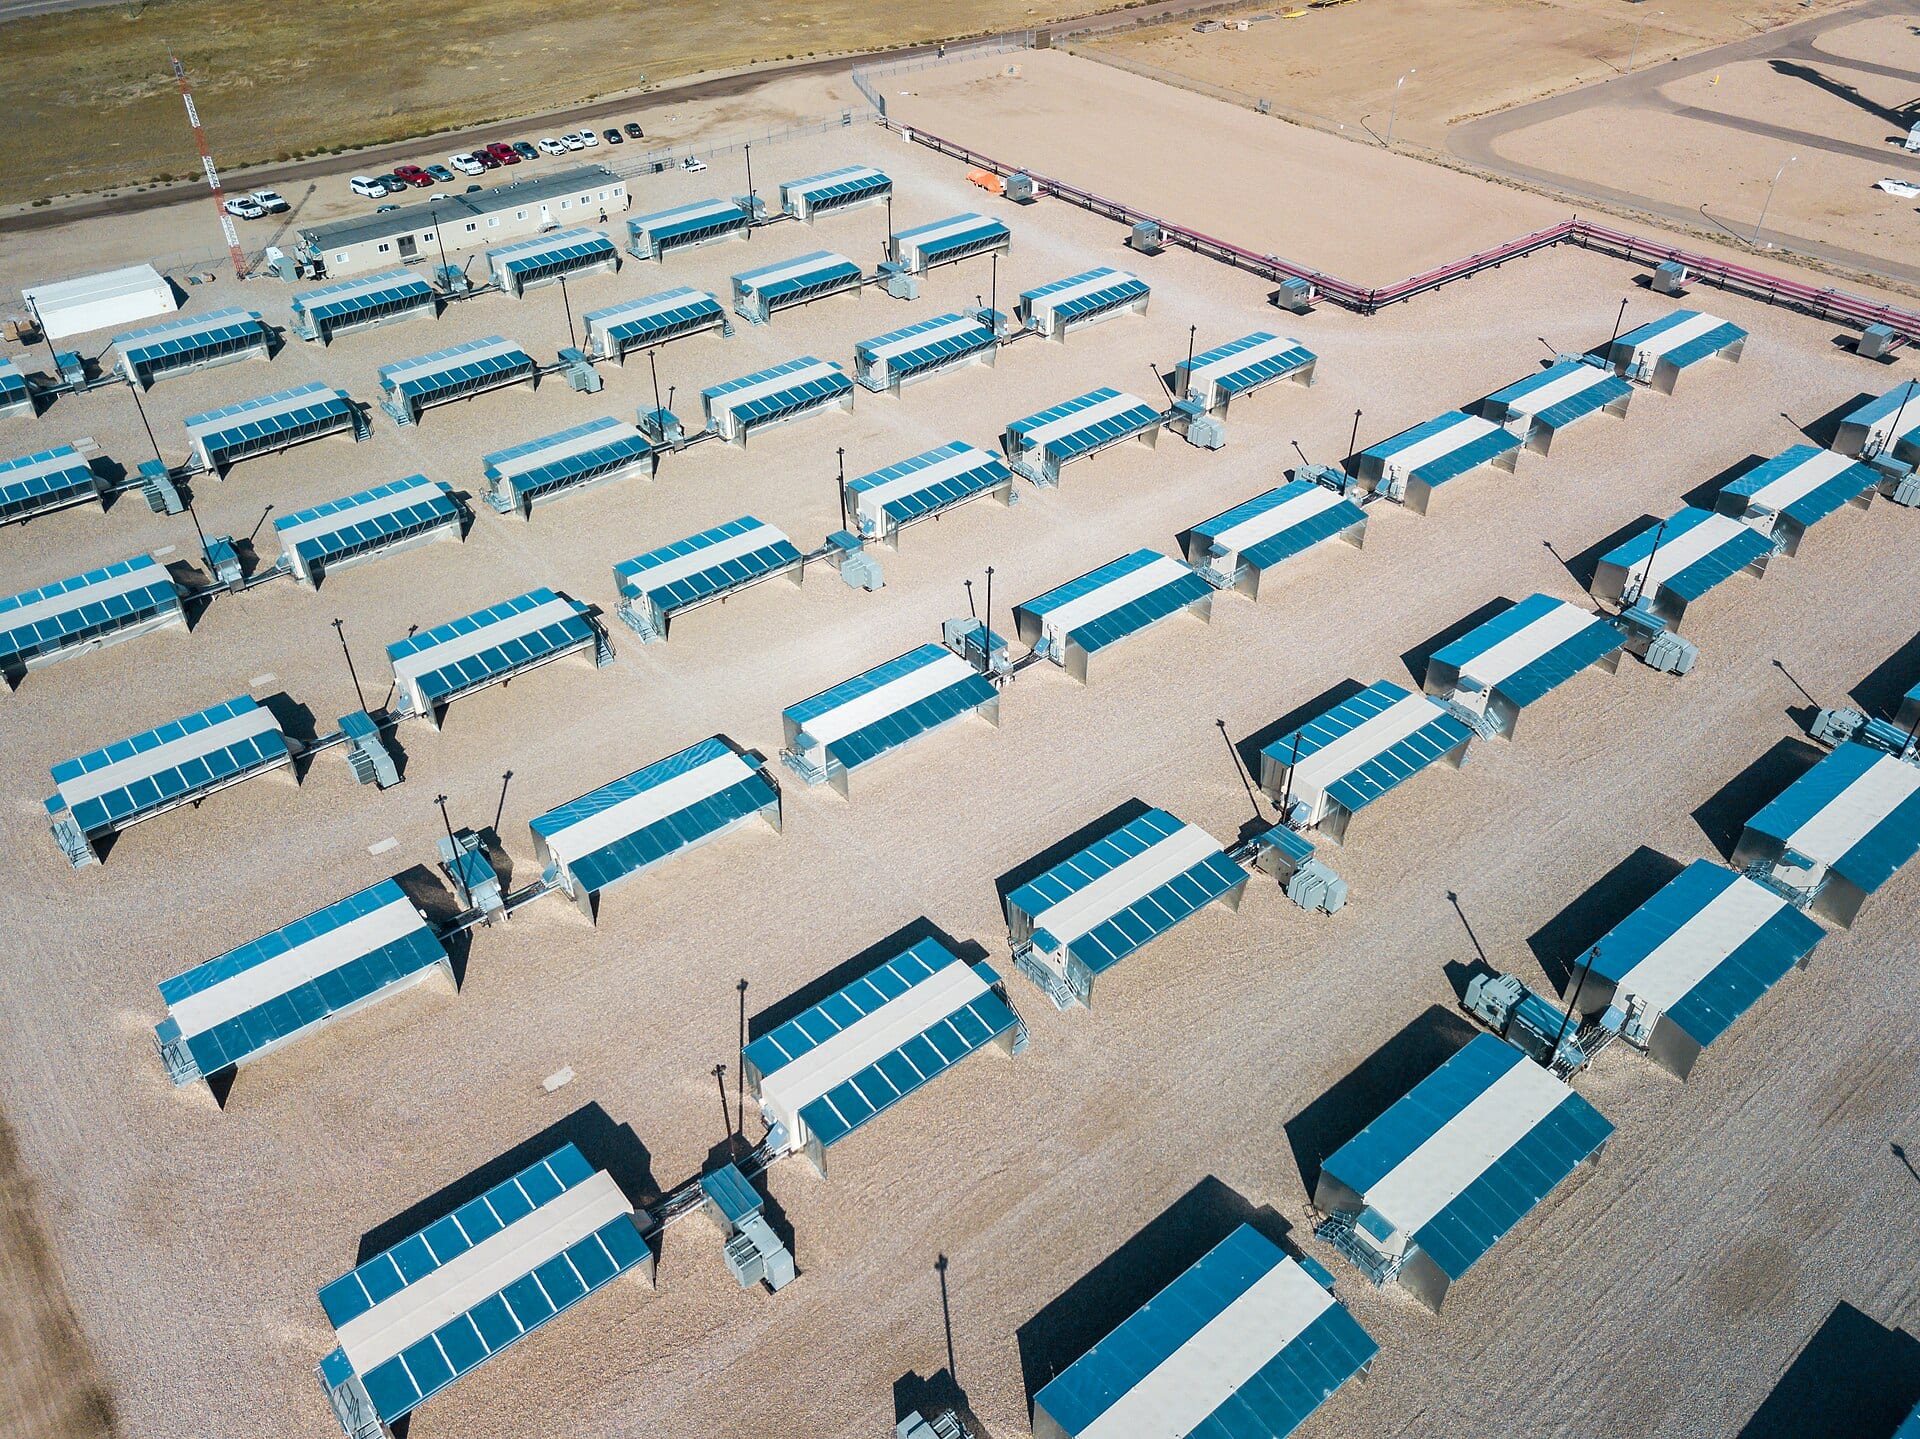
It doubled the unnamed tenant's commitment to 704 MW, all of it high investment grade, and lifted the portfolio's expected base-term contract value to about $26.6 billion 7. What is new since July is origination: capacity under exclusivity rose 1,300 MW to 3,180 MW, and Hut 8 agreed to buy two energized West Texas sites, up to 230 MW, for up to $180 million from affiliates of the bankrupt crypto firm Poolin through a Chapter 11 sale, closing as early as this quarter 6.
704 MW is leased against a 3,180 MW pipeline
Data
| Value | |
|---|---|
| Leased to tenants | 704 MW |
| In construction | 1,330 MW |
| Under exclusivity | 3,180 MW |
| West Texas sites under contract | 230 MW |
Revenue is falling and profit rides bitcoin's price
Quarterly revenue has slipped from an average of $86 million in late 2025 to about $72 million this year: $71.1 million in the third quarter, down from $83.5 million a year earlier and below the $76 million to $77 million analysts expected 68. Net income of $189.5 million rests on $413.8 million of mostly unrealized digital-asset gains; a quarter earlier the same marks drove a $177.1 million loss 46. Stripped of them, adjusted EBITDA was $33.0 million, against $105.5 million of interest expense 6.
Revenue peaked at $88.5 million in late 2025 and has slid back to $71 million
Data
| Revenue | |
|---|---|
| Q4 '24 | $32M |
| Q1 '25 | $22M |
| Q2 '25 | $41M |
| Q3 '25 | $83.5M |
| Q4 '25 | $88.5M |
| Q1 '26 | $71M |
| Q2 '26 | $74.9M |
| Q3 '26 | $71.1M |
Everything rides on the 2027 delivery dates
No rent is owed until the data halls are built. First rent is due when River Bend, anchored by a lease from the AI-cloud firm Fluidstack that Google backstops, delivers its first data hall in the second quarter of 2027; Beacon Point Phase 1 follows in the third quarter of 2027 and Phase 2 in mid-2028 56. About $6.6 billion of cash and short-term investments must carry 1,330 MW of construction to those dates 6. Chief Executive Asher Genoot set the bar himself in August: "Delivery is now our central priority" 4.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.