Only $34 billion of Micron's $134 billion contract floor lands in fiscal 2027 versus $275.5 billion consensus
Citi raised its 2027 supply forecasts for Samsung and SK hynix on November 3 and still called memory undersupplied, but the same revision halved its DRAM gap. Dan Niles puts CXMT's 20%-by-2028 DRAM target on Micron's record year, and Micron's 10-K shows only about $34 billion of a $134 billion contract floor falls due within twelve months.
 Vincent Jiang · 4 min read
Two calls read one market in opposite ways
Micron+4.49% — Micron, up 4.49 percent today rose 2.42% on November 3 and SK hynix+4.44% — SK hynix, up 4.44 percent today gained about 2.8%, while Samsung Electronics−4.15% — Samsung Electronics, down 4.15 percent today slid 4.15% as Apple's−2.33% — Apple, down 2.33 percent today margin warning rippled through global tech 12. Into that split session came two research calls built on the same facts. Citi−0.32% — Citi, down 0.32 percent today kept its call that memory stays undersupplied through 2027 2. Dan Niles, founder of Niles Investment Management, granted the bulls their buybacks and their long-term agreements, then named his worry: "China is bringing on a lot of capacity" 1.
Citi's revision carries its own end date
Citi raised its 2027 supply forecasts for Samsung and SK hynix and still sees a shortfall: DRAM, the workhorse memory in servers and phones, growing 24% in supply against 28% in demand, with the fulfillment ratio, the share of demand suppliers can actually fill, near 70% 27.
The same note halved the gaps it tracks, cutting the 2027 DRAM shortage to -3.8% from -8.7% and NAND to -3.3% from -6.1%, while lifting 2027 DRAM capex growth to 55% 2. Citi keeps the call because suppliers are signing long-term agreements rather than chasing prices; the direction of its own numbers runs toward balance 2.
China's deadline lands on Micron's record year
Niles puts CXMT−7.00% — CXMT, down 7.00 percent today, the Hefei-based, state-affiliated Chinese DRAM maker, at about 8% of the market and targeting "20% by 2028" 13. HSBC already counts close to 10%, up from about 4% a year ago, after a July Shanghai debut that rose 466% and briefly made CXMT China's most valuable listed company 4. Niles also flags YMTC, China's state-affiliated NAND maker, which he says aims to be No. 1 in NAND by 2028 13.
The timing is the problem. Consensus has Micron's earnings per share climbing from $75.52 in fiscal 2026 to a record $207.76 in fiscal 2028, and that record was built on prices: DRAM selling prices rose about 180% last fiscal year on bit shipments up in the mid-20% range, while quarterly gross margin climbed from 18.5% to 86.8% in eleven quarters 135.
Micron's quarterly gross margin has climbed from 18.5% to 86.8% in eleven quarters
Data
| Gross margin | |
|---|---|
| Q1 '24 | 18.5% |
| Q2 '24 | 26.9% |
| Q3 '24 | 35.3% |
| Q4 '24 | 38.4% |
| Q1 '25 | 36.8% |
| Q2 '25 | 37.7% |
| Q3 '25 | 44.7% |
| Q4 '25 | 56% |
| Q1 '26 | 74.4% |
| Q2 '26 | 84.6% |
| Q3 '26 | 86.8% |
The floor covers less than half the consensus year
The bull case rests on a document. The 10-K Micron filed on October 9 carries about $134 billion of contracted future revenue at committed volumes and minimum prices, under take-or-pay agreements where customers pay even if they take no chips 3. As recently as September 23, Citi counted 16 signed agreements with roughly $100 billion of cumulative minimums across 14 of them 6. A year earlier, Micron's remaining performance obligations were "not material," so the entire floor was built inside fiscal 2026 3.
Take-or-pay does not mean revenue in 2027
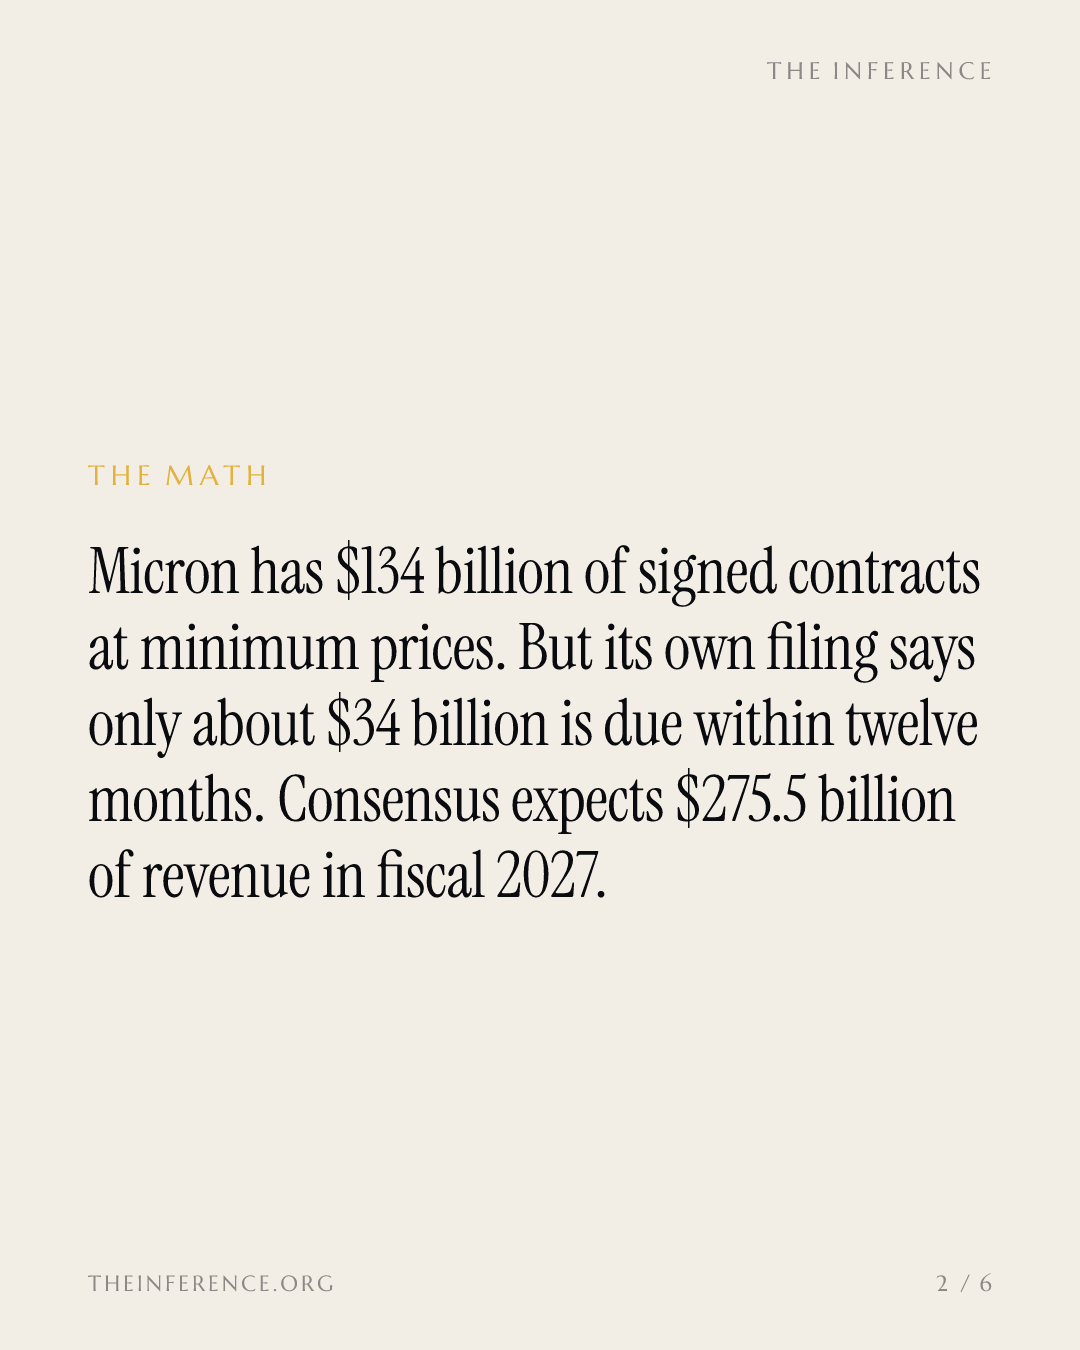
The due dates are thinner than the headline. About one-fourth, roughly $34 billion, is expected to become revenue within twelve months, against $275.5 billion of consensus fiscal 2027 revenue 31. Inside the $134 billion, $13 billion is already banked as customer deposits, repayable mostly between 2029 and 2031, with $7 billion of letters of credit behind the deals 3.
Even if every committed dollar landed on time, the floor would cover less than half of the consensus year. The Inference walked the committed-output case on November 2; the due-date arithmetic is the half it lacked (The Inference, November 2, 2026) 3.
Micron's $134 billion contract floor covers less than half its consensus 2027
- Estimate
Data
| Value | |
|---|---|
| Due within 12 months | $34B |
| Total contract minimums | $134B |
| Consensus FY2027 revenue (estimate) | $275.5B |
The 10-K answers the bear
The filing argues the floor prices alone would suffice: gross margins on the price-band agreements, "even at floor pricing levels," should beat the peak of any past cycle 3. Cash and marketable investments hit $73.45 billion on September 3, from $11.94 billion a year earlier 3.
SK hynix, which supplies HBM, the stacked memory that sits beside AI processors, just posted 104.6 trillion won of quarterly revenue at an 80% operating margin, calls its DRAM and HBM sold out through 2029, and expects demand to outrun supply through 2030 78. Niles's precedent stands anyway: the last time Micron traded near 5 times forward earnings, at the 2017 and 2018 peak, earnings per share fell 79% by fiscal 2020 1.
December 16 settles it
Micron reports fiscal first-quarter results on December 16, and one line settles the argument: management's outlook that industry DRAM bit shipments grow only in the low-20% range in both 2027 and 2028, keeping supply behind demand 1. Hold that outlook, and the shortage outlasts Niles's clock. Cut it, and Citi's narrowing gap arrives early. Until then, each revision of that gap is the tell.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.